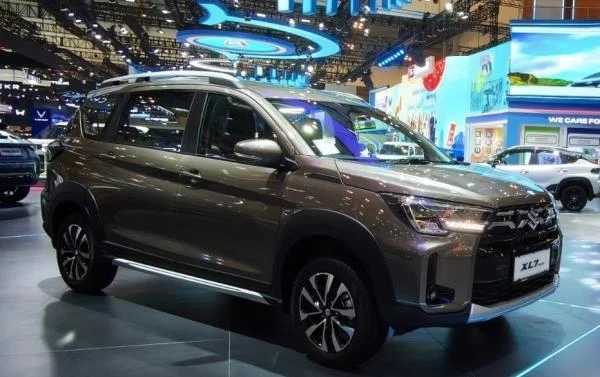
The Indonesian automotive landscape is undergoing a profound transformation, characterized by the influx of new global manufacturers and the rapid transition toward electrification. In this high-stakes environment, PT Suzuki Indomobil Sales (SIS) has identified its strategic stronghold: a robust, deeply rooted presence in regions outside the capital city. While many competitors focus their resources on the high-density urban sprawl of the Greater Jakarta area (Jabotabek), Suzuki has successfully pivoted to a decentralized strategy, with 70 percent of its national sales volume currently generated from diverse regional territories across the archipelago.
This geographic distribution, as articulated by Randy R. Murdoko, Marketing & Value Chain 4W Department Head at PT SIS, underscores a deliberate long-term investment in infrastructure, supply chains, and customer service networks that extend far beyond the metropolitan hubs. By maintaining a footprint that encompasses even the most remote islands, Suzuki has insulated itself against the volatility of the Jakarta-centric market, creating a sustainable model that balances national brand visibility with localized dominance.
The Strategic Shift Toward Regional Penetration
For decades, the Indonesian automotive market was synonymous with Jakarta and its satellite cities. The concentration of wealth, infrastructure, and dealership networks made this region the primary battlefield for automotive giants. However, as the market matures, the saturation of urban centers has forced manufacturers to re-evaluate their geographic priorities.
Suzuki’s data reveals a clear divergence from the industry norm. While Jabotabek continues to be a vital market, contributing approximately 30 percent of the company’s total sales, it is no longer the sole engine of growth. The remaining 70 percent, derived from Sumatra, Kalimantan, Sulawesi, and the eastern islands of Indonesia, represents the backbone of Suzuki’s operational resilience.
This shift is not merely a byproduct of changing demographics but a result of a concerted effort to optimize the “Value Chain.” By establishing smaller, more efficient service hubs and parts warehouses in secondary and tertiary cities, Suzuki has lowered the barrier to entry for customers who previously had to travel hundreds of kilometers for vehicle maintenance. This approach has fostered deep-seated brand loyalty in regions where vehicle reliability and after-sales accessibility are the primary purchase drivers.
The Competitive Landscape: Navigating New Entrants
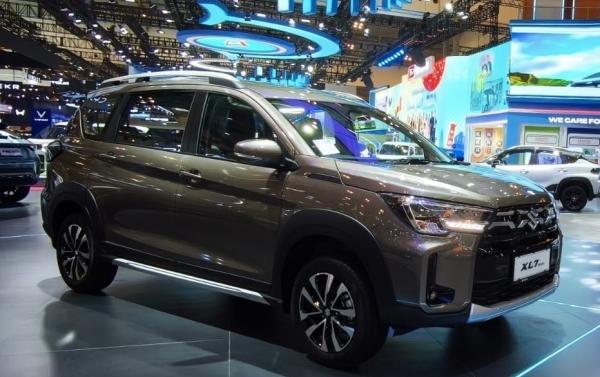
The arrival of new automotive brands, particularly from China and South Korea, has introduced a wave of aggressive pricing and high-tech vehicle specifications into the Indonesian market. These newcomers are primarily leveraging the "digital-first" approach, targeting tech-savvy urban millennials with premium features.
In contrast, Suzuki’s strategy focuses on the utility and endurance of its product lineup—vehicles such as the Carry, which remains a staple in the small business and logistics sector, and the Ertiga, a family-focused MPV. By focusing on the "workhorse" segments, Suzuki has tapped into a market segment that is less sensitive to the ephemeral trends of the tech-heavy urban market and more concerned with Total Cost of Ownership (TCO) and vehicle longevity.
Industry analysts observe that while new brands may win the "spec sheet" battle in Jakarta, they often struggle to build the extensive service infrastructure required to maintain trust in more remote areas. Suzuki’s decades-long presence in these regions serves as a protective moat, as consumers in provinces are historically hesitant to purchase vehicles from brands with sparse service networks.
Chronology of Market Evolution in Indonesia
The trajectory of the Indonesian automotive market can be categorized into several distinct phases:
- The Era of Consolidation (1990s–2000s): Japanese manufacturers established a near-monopoly, building large-scale manufacturing facilities in West Java. During this period, the focus was almost entirely on the Java-Bali axis.
- The Infrastructure Boom (2010s): The government’s massive investment in the Trans-Java toll road and regional connectivity projects changed the logistics of automotive distribution. This allowed manufacturers to move vehicles more efficiently to the outer islands.
- The Diversification Phase (2020–Present): With urban saturation reaching a peak, automotive players began shifting their marketing budgets toward regional "tier-two" cities. Suzuki’s early commitment to these regions during this period has provided it with a significant head start in terms of customer acquisition and dealership loyalty.
Analyzing the Data: Why Regional Focus Matters
The reliance on a 70/30 sales split provides Suzuki with two distinct advantages: risk mitigation and market insulation.
Firstly, the Indonesian economy is not monolithic. When the Jakarta market experiences a slowdown due to policy changes, urban congestion, or economic cooling, regional economies—often driven by commodities, agriculture, or mining—may remain buoyant. By maintaining a presence across all major Indonesian islands, Suzuki effectively hedges its bets against regional economic downturns.
Secondly, the "last-mile" service capability is a competitive advantage that cannot be built overnight. In the automotive industry, the dealership network is the most capital-intensive asset to build. Suzuki’s decision to maintain coverage in smaller islands and rural districts acts as a significant entry barrier for new brands, which are currently restricted to major capital cities where they can achieve higher volume-per-dealer ratios.
Official Perspectives and Future Projections
Speaking on the company’s outlook, Randy R. Murdoko emphasized that the strategy is not just about sales volume, but about long-term customer relationships. "Because we cover so many territories, including the smallest regions and remote islands, we have built a level of trust that is deeply embedded in the local culture," he noted.
This philosophy is expected to guide Suzuki’s upcoming product launches. The industry anticipates that the brand will continue to prioritize vehicles that excel in rugged terrain and offer high fuel efficiency, catering to the needs of the regional consumer base rather than just the urban commuter.
Furthermore, as the Indonesian government pushes for the adoption of hybrid and electric vehicles (EVs), Suzuki is positioned to transition its regional customer base gradually. By introducing hybrid technology in established, popular models, the company aims to upgrade its existing regional loyalists rather than forcing them to adopt radical new technologies that may not be supported by local charging infrastructure.
The Broader Impact: Implications for the Industry
The success of Suzuki’s regional-heavy strategy offers a blueprint for the wider automotive industry. As Indonesia moves toward its goal of becoming a regional manufacturing hub, the reliance on regional markets will only increase. Brands that ignore the potential of the outer islands in favor of the hyper-competitive Jakarta market are likely to face stagnation as the urban market becomes increasingly crowded.
The implications for the Indonesian consumer are also positive. Increased competition in regional markets will likely lead to better after-sales support, improved spare parts availability, and a wider range of vehicle choices. As manufacturers follow Suzuki’s lead in investing in regional infrastructure, the overall quality of automotive services in Indonesia is expected to rise.
Conclusion: Sustaining Momentum
Suzuki’s ability to navigate the complexities of the Indonesian market is a testament to the importance of "feet on the ground." By understanding that the Indonesian market is not merely a collection of urban centers but a vast, diverse archipelago with distinct regional requirements, the company has secured a stable, long-term trajectory.
While the automotive sector faces inevitable challenges—ranging from global supply chain disruptions to the shifting regulatory landscape regarding emissions—Suzuki’s decentralized market presence provides a strong foundation. The company is not merely selling cars; it is maintaining a network of connectivity that spans the Indonesian archipelago. As the industry continues to evolve, this focus on reach, reliability, and regional commitment will likely remain the core pillar of Suzuki’s competitive strategy in the years to come.
As the industry looks toward the next decade, the metrics of success will likely shift from pure sales volume in capital cities to the depth of market penetration and the resilience of the service network. In this regard, Suzuki has effectively positioned itself as a legacy brand that is as relevant in the remote corners of the nation as it is in the heart of its most modern cities. The challenge moving forward will be to maintain this delicate balance, ensuring that the brand continues to modernize while honoring the regional trust it has spent decades cultivating.