The government of Indonesia has projected that the total volume of tax expenditures, encompassing various fiscal incentives and revenue foregone through tax relaxations, will reach Rp632 trillion by 2027. This figure marks a significant escalation from the revised estimations for 2026, which stood at approximately Rp576.4 trillion. The strategic allocation of these fiscal resources aims primarily to stimulate expansion within the domestic manufacturing sector, enhance industrial competitiveness, and insulate the broader national economy from ongoing global macroeconomic volatility.
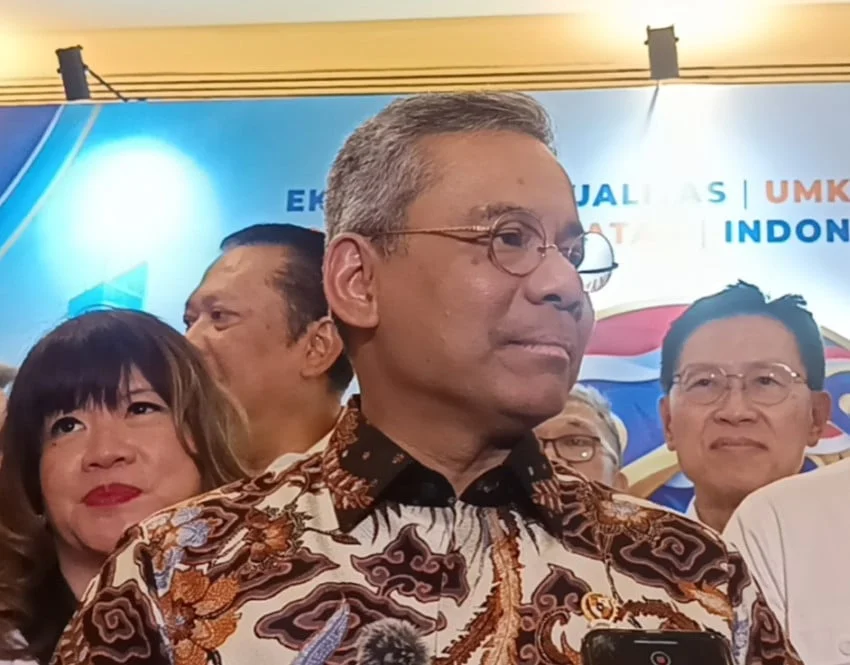
The official projection was announced by Deputy Minister of Finance Suahasil Nazara during his keynote address at the National Leadership Meeting (Rapimnas) of the Indonesian Chamber of Commerce and Industry (Kadin) held in Jakarta. Speaking to business leaders, policymakers, and economic analysts, Suahasil emphasized that the deployment of fiscal instruments remains a critical pillar of state intervention designed to bolster industrial capacity, encourage capital investments, and maintain corporate productivity amidst a complex international trade landscape.
Strategic Allocation and Sectoral Prioritization
According to the Ministry of Finance, the manufacturing sector will remain the primary beneficiary of these targeted tax expenditures. The state facilitates industrial growth through a suite of calibrated instruments, including tax holidays for pioneer industries, preferential effective Value-Added Tax (VAT) rates, and corporate income tax (PPh) exemptions on dividends.
Suahasil explained that these policy instruments are deliberately deployed to lower the cost of capital for businesses looking to upgrade their facilities, adopt advanced technologies, and integrate deeper into global supply chains. By shielding key operational phases from heavy tax burdens, the government intends to encourage long-term capital formation rather than short-term speculative gains.
The manufacturing industry has historically served as a vital engine for Indonesia’s Gross Domestic Product (GDP), absorbing millions of workers and driving export revenues. However, structural challenges—such as logistics bottlenecks, rising energy costs, and fluctuating external demand—have necessitated sustained government support. The projected escalation in tax expenditures to Rp632 trillion reflects an ongoing policy commitment to ensure that Indonesian manufacturing remains competitive against regional peers in Southeast Asia.
Broadening the Scope: Support for Micro, Small, and Medium Enterprises
Beyond heavy industry and large-scale manufacturing, the government’s fiscal expenditure framework explicitly incorporates provisions designed to nurture Micro, Small, and Medium Enterprises (MSMEs). These enterprises form the backbone of the domestic economy, contributing significantly to employment and grassroots economic activity.
During the Rapimnas Kadin forum, Suahasil highlighted the continuation of preferential tax treatments for smaller businesses. Specifically, the government maintains a final Income Tax (PPh Final) rate of 0.5 percent on gross turnover for businesses with an annual gross revenue below Rp4.8 billion. This specialized scheme offers a substantial relief compared to the standard corporate income tax rate of 22 percent levied on net profits.
Economic analysts note that the simplified 0.5 percent turnover tax reduces administrative compliance costs for small business owners, encouraging formalization among informal sector enterprises. By lowering the tax barrier for early-stage and medium-scale businesses, the state aims to foster a more resilient entrepreneurial ecosystem capable of weathering domestic consumption shifts.
Safeguarding Purchasing Power and Social Welfare
In addition to stimulating corporate investment and small business growth, a significant portion of the projected tax expenditure is dedicated to maintaining consumer purchasing power and supporting social welfare. Fiscal policy interventions are structured to reduce the cost burden on essential goods and services, thereby protecting vulnerable segments of the population from inflationary pressures.
The Ministry of Finance detailed that tax exemptions and reductions are applied across several vital consumer sectors. These include the waiver of Value-Added Tax on specific motor vehicles, residential housing targeted at low-income communities (Rumah Masyarakat Berpenghasilan Rendah), public transportation services, educational institutions, and healthcare services. Furthermore, the government continues to provide exemptions from the Final Income Tax on the transfer of land and buildings under qualifying conditions.
These targeted exemptions serve a dual purpose. On the supply side, they incentivize developers to construct affordable housing and encourage investment in public utility infrastructure. On the demand side, they preserve real disposable incomes for households, mitigating the impact of global commodity price fluctuations on domestic consumption.
Background Context and Chronological Evolution of Fiscal Policy
The announcement at the Kadin Rapimnas comes against the backdrop of Indonesia’s broader post-pandemic economic recovery strategy, which has increasingly relied on targeted fiscal stimuli rather than broad-based subsidies. Over the past several years, the Ministry of Finance has progressively refined its approach to tax expenditures, shifting from emergency crisis management measures toward structural industrial policies.
Chronologically, the expansion of tax expenditures aligns with the government’s long-term vision of transforming Indonesia into a high-value-added economy through downstreaming policies (hilirisasi). Initiated aggressively in the mining and mineral sectors, downstreaming has gradually expanded to agricultural and forestry products, requiring extensive capital investments that heavily depend on fiscal incentives such as tax holidays and import duty exemptions for capital goods.
In previous fiscal years, tax expenditures hovered around the Rp400 trillion to Rp500 trillion range, encompassing various social assistance programs administered through the tax code, customs exemptions for strategic projects, and sector-specific tax reliefs. The projected rise to Rp576.4 trillion in 2026 and Rp632 trillion in 2027 indicates a calculated acceleration in state-backed economic stimulation, synchronized with national medium-term development plans.
Responses and Perspectives from the Business Community
The business community, represented by leaders within the Indonesian Chamber of Commerce and Industry, has generally welcomed the government’s commitment to maintaining and expanding fiscal incentives. Industrial associations have long argued that high operational costs and complex regulatory environments require compensatory mechanisms to maintain international competitiveness.
Kadin representatives noted that while tax holidays and VAT relaxations are effective in attracting new investments, the predictability and transparency of administrative procedures remain crucial. Business leaders have emphasized that investors evaluate not only the nominal value of tax incentives but also the certainty of their implementation and the speed at which applications are processed by relevant government agencies, such as the Ministry of Finance and the Investment Coordinating Board (BKPM).
At the same time, fiscal watchdogs and economic researchers have offered nuanced perspectives on the rising trajectory of tax expenditures. While acknowledging the necessity of supporting manufacturing and MSMEs, analysts frequently remind policymakers of the importance of rigorous cost-benefit analyses. Because tax expenditures represent foregone state revenue, each fiscal incentive must be weighed against its measurable impact on job creation, technological transfer, and domestic value addition to ensure fiscal sustainability over the long term.
Macroeconomic Implications and Fiscal Sustainability
The projection of Rp632 trillion in tax expenditures for 2027 raises important considerations regarding fiscal management and budget discipline. Under Indonesian law, the state budget (APBN) deficit is legally mandated to be maintained below 3 percent of Gross Domestic Product, requiring the government to balance revenue collection efforts with expenditure commitments.
As tax expenditures rise, the Directorate General of Taxes faces the dual challenge of administering broad-based exemptions while simultaneously expanding the domestic tax base to secure necessary state revenues for infrastructure and social spending. To reconcile these objectives, the Ministry of Finance has pursued administrative modernization programs, enhanced data integration across government agencies, and implemented compliance improvement strategies such as the ongoing rollout of the Core Tax Administration System (CTAS).
The strategic bet underpinning the 2027 projections is that targeted tax expenditures will generate positive secondary economic effects. By lowering production costs and encouraging capital formation in high-multiplier sectors like manufacturing, the policy is expected to stimulate broader economic activity, expand corporate profits, and ultimately generate higher baseline tax revenues in subsequent fiscal cycles.
Ultimately, the realization of these fiscal objectives will depend on external economic conditions, including global supply chain stability, geopolitical stability, and the trajectory of international interest rates. As Indonesia navigates these complex global dynamics, the Ministry of Finance’s calibrated approach to tax expenditures will remain a central instrument in maintaining macroeconomic stability while pursuing ambitious industrialization goals.