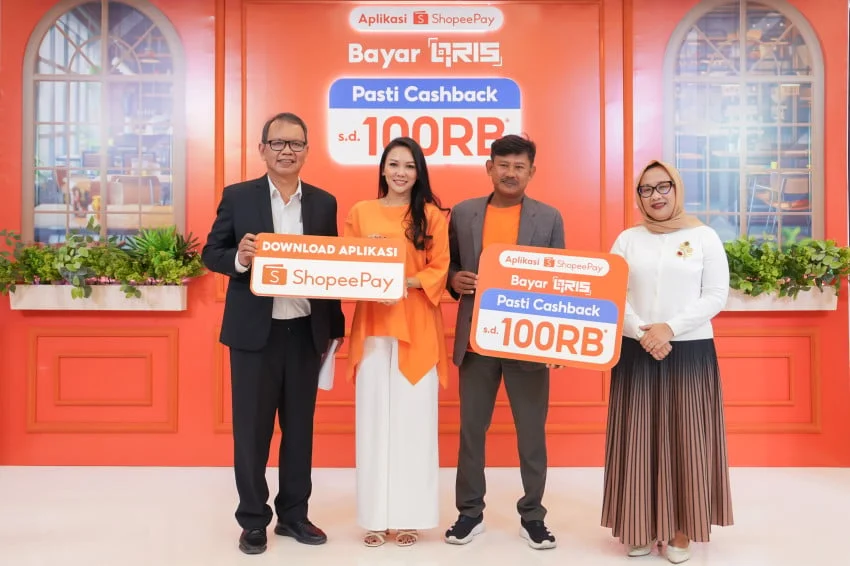
The landscape of financial transactions in Indonesia has undergone a seismic shift toward digitalization, primarily driven by the ubiquitous adoption of the Quick Response Code Indonesian Standard (QRIS). As Bank Indonesia (BI) continues to spearhead the national drive toward a cashless society, major digital wallet providers like ShopeePay have emerged as critical intermediaries. By integrating seamless payment solutions into a single, user-friendly application, ShopeePay is not only facilitating everyday consumer convenience but is also serving as a vital bridge for Micro, Small, and Medium Enterprises (MSMEs) to transition into the formal digital economy. This transformation was underscored during the recent industry forum titled "Cara Baru Manfaatkan QRIS: Pengguna & Pengusaha UMKM Pasti Untung," held in Jakarta on September 16, where stakeholders highlighted the strategic importance of standardized digital payments in achieving national financial inclusion goals.
The Evolution of QRIS in the Indonesian Financial Landscape
The introduction of QRIS by Bank Indonesia in August 2019 was a milestone aimed at consolidating the fragmented digital payment ecosystem. Prior to its inception, the market was saturated with proprietary QR codes from various e-wallets, forcing merchants to display multiple QR stands and complicating reconciliation for business owners. The standardization provided by QRIS allowed for interoperability, where any QRIS-enabled app could process payments regardless of the merchant’s payment service provider.
Over the past five years, the adoption curve has been steep. From local wet markets and street-side vendors to major retail chains, QRIS has become the standard language of commerce. The systemic push by the central bank has focused on four pillars: efficiency, security, inclusivity, and integration. By lowering the barriers to entry for small businesses, the policy has effectively democratized access to financial services, allowing even the smallest businesses to maintain a digital ledger of transactions, which is a prerequisite for future credit access and financial health.
Insights from the September 16 Forum
The "Cara Baru Manfaatkan QRIS" event served as a platform for policy makers and industry players to reflect on the progress of digital penetration. Fitria Irmi Triswati, Executive Director of the Payment System Policy Department at Bank Indonesia, emphasized that the current growth of QRIS is not merely a trend but a foundational shift in how the Indonesian economy operates.
"The development of QRIS is a central component of Bank Indonesia’s strategy to build a digital payment ecosystem that is inclusive, efficient, secure, and fully integrated," Triswati stated during the event. She highlighted the staggering statistic that 96.69% of the 45.46 million QRIS-registered merchants are categorized as MSMEs. This data point is critical; it demonstrates that the digitalization effort has successfully penetrated the grassroots level of the economy, providing small-scale entrepreneurs with the same technological advantages previously reserved for large corporations.
The Role of ShopeePay in Facilitating Digital Adoption
ShopeePay has strategically positioned itself as a primary enabler of this transition. By embedding QRIS technology within its core mobile application, ShopeePay offers more than just a payment gateway; it offers a comprehensive financial toolset. For the average Indonesian consumer, the convenience of using a single app to pay for transport, groceries, utility bills, and e-commerce purchases creates a "stickiness" that drives consistent usage.
For the MSME sector, ShopeePay provides more than just the ability to accept payments. It offers a dashboard for sales monitoring, simplified fund settlement, and integration with the wider Shopee ecosystem, which includes logistics support and access to a massive customer base. By leveraging the familiarity of the Shopee platform, small business owners are finding it easier to transition from cash-only operations to digital, transparent systems. This shift is essential for "financial formalization," where businesses build a transaction history that can eventually be used by banks and fintech lenders to assess creditworthiness.

Supporting Data and Market Trends
The acceleration of QRIS adoption is supported by robust data from the central bank and independent financial analysts. As of the third quarter of 2024, the volume of QRIS transactions in Indonesia has seen double-digit growth year-on-year. Several factors contribute to this:
- Merchant Penetration: The expansion into rural areas and traditional markets (pasar tradisional) has been a key driver.
- Consumer Behavior: The post-pandemic shift toward touchless payments has become permanent, with consumers prioritizing safety and efficiency.
- Regulatory Support: Bank Indonesia’s policies, including the introduction of QRIS Tuntas (transfer, tarik tunai, setor tunai), have added functionality beyond simple payments, allowing for basic banking services at the point of sale.
The reliance on MSMEs as the backbone of this ecosystem is not accidental. In Indonesia, MSMEs contribute over 60% of the national GDP. Therefore, by digitizing this sector, the government is essentially digitizing the core of the Indonesian economy, which leads to better tax compliance, improved economic data tracking, and higher overall economic productivity.
Challenges and Future Implications
Despite the rapid success, the ecosystem faces ongoing challenges. Cybersecurity remains a primary concern as the frequency of digital transactions increases. Both Bank Indonesia and payment service providers like ShopeePay are under continuous pressure to enhance fraud detection mechanisms and educate the public on secure digital habits.
Furthermore, there is the "digital divide" issue. While urban centers have high adoption rates, infrastructure limitations in remote regions remain a hurdle. Providing reliable internet connectivity is essential for the continued expansion of the QRIS network. Analysts suggest that the next phase of development will likely involve "embedded finance," where payment data is used to provide instant micro-loans or insurance products tailored specifically to the needs of the merchant or consumer.
The implications for the broader economy are significant. A fully digitalized payment system reduces the cost of printing and distributing physical currency, minimizes the risk of counterfeit money, and provides the government with real-time economic data that can inform more precise fiscal and monetary policies. For the merchant, it eliminates the "cash-handling" risk—the theft or loss of physical money—and provides a professionalized audit trail that can be used for business expansion.
Conclusion: A Collaborative Future
The synergy between regulatory bodies like Bank Indonesia and private entities like ShopeePay represents a model for public-private partnership in the digital age. By focusing on accessibility and utility, these stakeholders have transformed the way daily commerce is conducted in Indonesia. The goal, as voiced at the Jakarta forum, is to ensure that no segment of society is left behind.
As the ecosystem matures, the focus will likely shift from simple volume growth to quality of service and the integration of value-added financial services. For the Indonesian consumer, the "Cara Baru" or "New Way" of transacting is no longer an alternative—it has become the primary method for engaging with the economy. As QRIS continues to integrate into the daily lives of millions, the foundation for a modern, digital-first Indonesian economy is being firmly laid, promising a future of greater financial inclusion and economic resilience. The success of this initiative will be measured not just by the number of QR codes displayed at shop counters, but by the tangible improvements in the daily lives of the millions of entrepreneurs and consumers who now participate in a safer, faster, and more efficient digital marketplace.