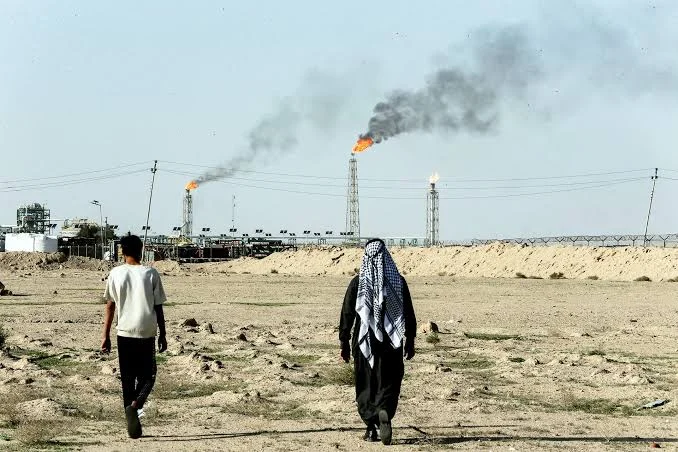
Global crude oil benchmarks advanced significantly during Friday trading sessions, extending a robust upward trajectory and positioning the energy market for its fourth consecutive monthly gain. The surge is primarily driven by mounting geopolitical anxieties regarding global energy supplies, catalyzed by the persistent and deepening conflict between the United States and Iran. Compounding these supply-side fears, a fresh wave of maritime attacks targeting commercial vessels in the strategically vital Strait of Hormuz has severely heightened risks surrounding the distribution of petroleum from the Persian Gulf region. This latest flare-up comes at a time of profound uncertainty regarding any diplomatic resolution to hostilities, leaving international energy markets highly volatile and vulnerable to sudden supply shocks.
Market participants and commodities analysts are increasingly pricing in the likelihood of prolonged military friction, particularly in the shadow of impending political milestones in Washington. Ole Hansen, Head of Commodity Strategy at Saxo Bank, emphasized the nervous sentiment gripping the trading floors. The oil market is becoming increasingly engulfed by apprehension ahead of the United States midterm elections, a period historically associated with heightened political posturing and strategic maneuvering. Numerous institutional investors and geopolitical risk analysts harbor strong expectations that targeted military actions by the United States against Iranian infrastructure and strategic assets could intensify significantly in the aftermath of the legislative elections, potentially triggering a broader regional conflagration.
Reflecting this tense macroeconomic and geopolitical climate, market data at 12:36 GMT on Friday revealed substantial upward pressure across major futures contracts. The front-month Brent crude futures contract for December delivery, slated to expire on Friday, climbed USD2.26, or roughly 2%, to settle at USD117.14 per barrel. Simultaneously, the more actively traded Brent contract for January delivery appreciated by USD2.30, closing at USD113.10 per barrel. Benchmark American crude, West Texas Intermediate (WTI), mirrored these gains, rising USD1.94, or 1.9%, to reach USD103.94 per barrel. On a monthly aggregation basis, the performance underscores the severity of the supply squeeze: Brent is on track to post an impressive monthly advance of approximately 13%, while WTI is poised to record a staggering surge of roughly 15% for the month of October.
Chronology of Maritime Escalation in the Persian Gulf
The anxiety gripping global commodity desks reached a boiling point following a confirmed security incident in the Strait of Hormuz, a critical maritime chokepoint through which approximately one-fifth of the world’s petroleum passes. According to reports disseminated by the United Kingdom Maritime Trade Operations (UKMTO), a commercial oil tanker transiting the narrow waterway was struck by an explosive device deployed from an unidentified small craft. While the UKMTO verified the occurrence of the attack, international maritime authorities have not yet definitively attributed responsibility to a specific state or non-state actor.
Maritime security sources and intelligence analysts have highlighted the alarming nature of the incident, noting it to be the first successfully executed attack utilizing a magnetic mine, or limpet mine, against commercial shipping in the vital corridor since the outbreak of open hostilities between the United States and Iran in February. The deployment of limpet mines signifies a sophisticated tactical capability, demonstrating that commercial vessels remain acutely vulnerable despite heightened naval patrols and multinational coalition escorts operating within the Gulf region.
The timeline of the current crisis traces back to the breakdown of diplomatic frameworks earlier in the year, culminating in direct military engagements in February. Since then, the conflict has steadily evolved from localized skirmishes into a persistent war of attrition that directly threatens the flow of hydrocarbons. The recent employment of specialized naval mines in the Strait of Hormuz marks a dangerous escalation, transitioning the theatre of operations from missile and drone exchanges to asymmetric maritime sabotage designed to disrupt global supply chains covertly and effectively.
Expert Analysis and Industry Perspectives
Energy market analysts and institutional researchers have been swift to evaluate the structural implications of these developments. Saul Kavonic, Head of Energy Research at MST Marquee, pointed out that the relentless continuation of military actions in and around the Strait of Hormuz, coupled with a complete absence of viable diplomatic pathways, ensures that risk premiums will remain firmly baked into oil valuations. Kavonic noted that the market is currently compelled to price in a worst-case scenario where military escalation spirals further out of control over the coming weeks and months, effectively forestalling any potential correction in prices.
Echoing this cautious outlook, Giovanni Staunovo, a commodities analyst at UBS, underscored that the balance of risks remains skewed heavily toward further escalation and acute supply disruptions. Staunovo observed that diplomatic channels appear entirely stalled, noting that high-ranking Iranian officials have exhibited little to no confidence or willingness regarding the prospect of securing a durable diplomatic framework or de-escalation agreement with the United States in the near term. This diplomatic deadlock removes a crucial psychological floor for the market, leaving traders with little choice but to hedge aggressively against prolonged supply losses.
Broader Economic Implications and the Global Macroeconomic Outlook
The sustained elevation of crude oil prices above the USD100-per-barrel threshold carries profound macroeconomic consequences for the global economy, which is already grappling with persistent inflationary pressures, sluggish post-pandemic recoveries, and tightening monetary policies implemented by central banks worldwide. Energy costs permeate every sector of international commerce, acting as a foundational input for manufacturing, transportation, petrochemicals, and agriculture.
International financial institutions have begun issuing stern warnings regarding the compounding effects of high energy costs on global stability. Earlier projections from the World Bank and other multilateral economic bodies have highlighted how elevated commodity prices can trigger systemic shocks. In related economic forecasts, warnings have been sounded regarding broader commodity indices potentially experiencing dramatic upward adjustments, threatening to ignite a severe global food security crisis as fertilizer production, agricultural machinery operation, and food transport costs scale exponentially alongside petroleum prices.
For oil-importing nations across Asia, Europe, and the Americas, the continuous climb in Brent and WTI benchmarks translates directly into higher domestic fuel prices, elevated electricity generation costs, and a renewed spike in headline inflation figures. Central bankers, who had hoped to pivot toward more accommodative monetary stances, now find themselves constrained by the risk of imported energy inflation unmooring long-term inflation expectations. This dynamic increases the likelihood of prolonged high interest rates, which in turn dampens global economic growth and heightens the risk of a synchronized recession.
Furthermore, the structural shift in energy trade flows resulting from the protracted US-Iran conflict forces consuming nations to re-evaluate their strategic petroleum reserves and seek alternative, albeit often more costly, supply arrangements. Non-OPEC producers, particularly in the Americas, face mounting pressure to ramp up production to offset Middle Eastern shortfalls, though physical infrastructure and lead times mean such adjustments cannot happen overnight.
Outlook for the Energy Market
As the geopolitical landscape remains fraught with hazard and the Strait of Hormuz continues to serve as a primary flashpoint for asymmetric warfare, market observers anticipate that volatility will remain the defining characteristic of the global oil trade. With upcoming political events in the United States serving as a focal point for potential military policy shifts, and with regional actors showing minimal inclination toward compromise, the path of least resistance for energy prices appears skewed to the upside. Stakeholders across the energy value chain, from upstream producers to downstream industrial consumers, must navigate an exceptionally complex and high-risk operational environment for the foreseeable future.