The ongoing geopolitical escalation and military conflict in the Middle East have exposed the profound vulnerability of South Asia’s energy infrastructure, casting a long shadow over the economic stability of nations that are home to nearly two billion people. Representing approximately 23 percent of the global population, the countries of India, Pakistan, Bangladesh, and Nepal have historically relied heavily on fossil fuel imports originating from the Persian Gulf. Even prior to the outbreak of direct military confrontations involving Iran and other regional actors, this demographic giant depended on maritime chokepoints—most notably the Strait of Hormuz—to fuel its industries, generate electricity, and sustain daily life for hundreds of millions of citizens. Today, as conflict disrupts vital shipping lanes and pushes global energy markets into volatility, the structural limits of South Asia’s energy security models are being severely tested.
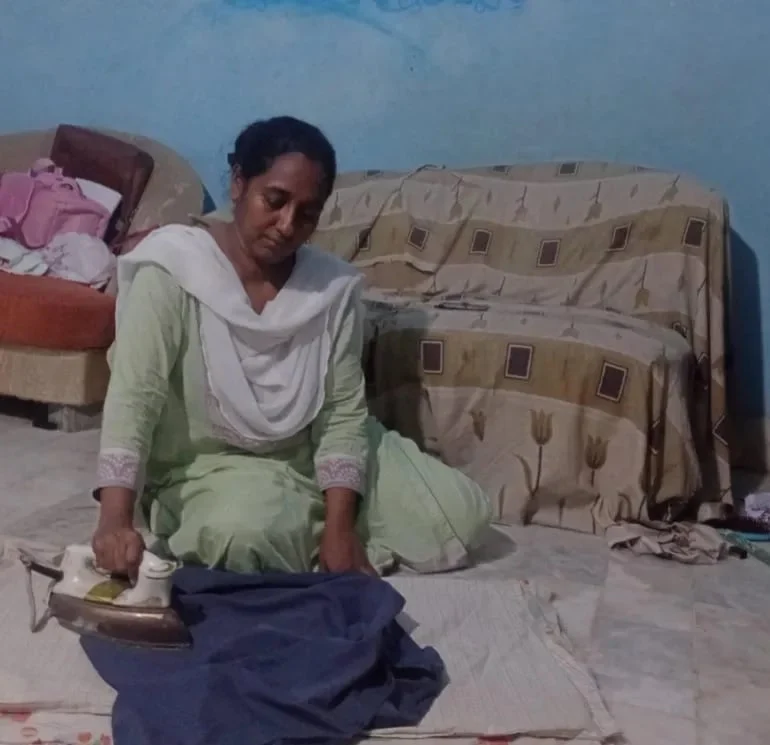
The human dimension of this macro-level crisis is visible in urban centers across the region, from the bustling port city of Karachi in southern Pakistan to the industrial hubs of northern India and the garment-producing zones of Bangladesh. Citizens like Sajida Jibran, a 45-year-old domestic worker navigating soaring inflation and energy tariffs in Karachi, represent the downstream reality of geopolitical shocks thousands of miles away. As electricity grids strain under fuel shortages and the cost of liquefied natural gas (LNG) spirals upward, ordinary households bear the brunt of an energy crunch that threatens to derail post-pandemic economic recoveries across the subcontinent.
Vulnerability and Differential Dependence Across South Asia
While the countries of South Asia share a common reliance on Middle Eastern hydrocarbons, the degree, structure, and resilience of their import dependencies vary significantly. Understanding how each nation sources its energy illuminates why the regional impact of the Middle Eastern conflict is unevenly distributed, yet universally disruptive.
India, as the world’s third-largest importer of crude oil, occupies a central position in global energy markets. New Delhi imports approximately 85 percent of the crude oil it consumes to drive its rapidly expanding industrial economy. Historically, the primary arteries of India’s energy supply have run through the Persian Gulf, with major producers such as Iraq, Saudi Arabia, the United Arab Emirates (UAE), and Kuwait providing the bulk of its liquid fuels. Additionally, Qatar has served as the cornerstone of India’s liquefied natural gas imports, supplying clean-burning fuel crucial for urban power generation and fertilizer production.
However, over recent years, Indian energy strategists have actively diversified their supply portfolios. New Delhi’s pragmatic diplomatic posture has allowed it to tap into non-traditional markets, securing substantial volumes of discounted crude oil from Russia, alongside traditional imports from African and American producers. This diversification offers India a degree of insulation that its neighbors largely lack, though it remains acutely vulnerable to extreme price spikes and supply disruptions in maritime transit routes like the Strait of Hormuz.
Pakistan presents a more precarious picture. The South Asian nation relies heavily on imported energy to meet its domestic and industrial power requirements, depending on a continuous influx of crude oil, refined petroleum products, and LNG. Historically, strategic partnerships with Saudi Arabia, the UAE, and Kuwait have secured vital petroleum supplies, often bolstered by deferred payment facilities that ease Islamabad’s acute foreign exchange pressures. Simultaneously, long-term supply contracts with Qatar have been essential for securing LNG imports. Unlike India, Pakistan’s ability to pivot to alternative global spot markets is severely constrained by severe balance-of-payments challenges, foreign reserves depletion, and IMF-mandated fiscal austerity. Consequently, any constriction of Gulf energy flows translates rapidly into rolling blackouts, industrial shutdowns, and inflationary spirals within Pakistan.
Bangladesh, meanwhile, faces a different structural dilemma. While the country possesses domestic natural gas reserves that have historically fueled its power sector and heavy industries, rapid economic growth and depleting local fields have forced Dhaka to become a net importer of energy. Bangladesh has increasingly turned to the global spot market and long-term contracts for LNG to bridge the widening gap between domestic supply and surging demand. Because its import infrastructure is relatively new and its financial buffers are limited, prolonged disruptions in Middle Eastern energy corridors pose an immediate threat to Bangladesh’s export-oriented manufacturing sectors, particularly its critical textile and garment industries.
Nepal, landlocked and lacking direct access to maritime shipping routes, is indirectly impacted through its heavy economic integration with India. Nearly all of Nepal’s petroleum product requirements are imported directly from Indian refineries via cross-border pipelines and tanker trucks. Any disruption to India’s crude supply or refining capacity ripples immediately northward, causing fuel shortages, transport bottlenecks, and price surges in the Himalayan nation.
Chronology of the Crisis: From Regional Tensions to Supply Chain Collapse
The current vulnerability of South Asia’s energy corridors is the culmination of decades of strategic reliance compounded by a rapid escalation of Middle Eastern hostilities.
In the years leading up to the current conflict, maritime security analysts frequently warned about the fragility of the Strait of Hormuz—a narrow waterway through which roughly a fifth of the world’s petroleum passes daily. Despite these warnings, South Asian economies continued to deepen their energy ties with Gulf Cooperation Council (GCC) nations, driven by geographical proximity, competitive pricing, and established diplomatic channels.
As tensions involving Iran, regional militias, and Western powers intensified, the risk profile of the Persian Gulf shifted dramatically. The chronology of the unfolding crisis can be mapped through several critical phases:
- Pre-Existing Structural Reliance (2010–2023): South Asian economies experienced rapid urbanization and industrialization, causing domestic energy demands to outpace local production capabilities. Governments leaned heavily on long-term contracts with Gulf suppliers, locking in volumetric security while accepting the geopolitical risk inherent in Middle Eastern transit routes.
- Geopolitical Friction and Maritime Security Incidents (Late 2023–Early 2024): Incidents involving commercial shipping in the Red Sea and adjacent waters began driving up global freight rates, war-risk insurance premiums, and transit times. While initial disruptions affected Europe-bound trade, energy tankers servicing Asian markets also faced operational delays and heightened security protocols.
- Outbreak of Direct Conflict (Mid-2024 onwards): The direct expansion of military hostilities involving Iran significantly escalated threats to the Strait of Hormuz and surrounding airspace. Major shipping companies began pausing or rerouting voyages, forcing energy exporters to reconsider the safety of traditional maritime pathways.
- Current Impasse and Regional Fallout: South Asian governments are now confronting constricted supply volumes, soaring spot-market prices for LNG, and severe macroeconomic strains. Central banks across the region are forced to allocate precious foreign exchange reserves to cover inflated energy import bills, crowding out developmental spending and social welfare programs.
Economic Implications and Macroeconomic Fallout
The broader economic implications of the Middle Eastern energy crisis for South Asia extend far well beyond momentary fuel shortages. Energy is the lifeblood of modern industrial output, transportation, and agricultural irrigation; thus, sustained shocks to the energy supply chain trigger cascading effects throughout domestic economies.
First, the fiscal deficits of importing nations are widening at an unsustainable pace. When global crude oil and LNG prices surge due to Middle Eastern supply fears, government import bills skyrocket. In countries like Pakistan and Bangladesh, where foreign exchange reserves are already precarious, paying for inflated energy imports drains central bank coffers. This depletion diminishes the capacity to stabilize local currencies against the US dollar, importing further inflation through costlier food and raw material imports.
Second, domestic inflation is eroding the purchasing power of the working and middle classes. As electricity generation costs rise—driven by expensive imported fuel—utilities are forced to pass these costs onto consumers through tariff hikes. Small businesses, agricultural pump operators, and urban households experience an immediate squeeze on their disposable incomes. In Karachi, workers like Sajida Jibran find that a greater proportion of meager monthly wages must be allocated simply to basic utilities and transport, leaving less for food, healthcare, and education.
Third, industrial productivity is under severe threat. Unreliable power grids and expensive fuel inputs reduce the competitiveness of South Asian manufacturing on the global stage. Industries ranging from Indian steel mills to Bangladeshi garment factories face difficult choices: absorb higher energy costs, pass them onto international buyers risking a loss of market share, or curtail production altogether. Prolonged power rationing directly translates to lower gross domestic product (GDP) growth and potential job losses across formal and informal sectors.
Official Responses and Strategic Adaptations
Governments across South Asia are actively scrambling to mitigate the fallout through diplomatic engagement, fiscal adjustments, and strategic energy diversification.
In New Delhi, the Ministry of Petroleum and Natural Gas has maintained close communication with diplomatic partners in both the Middle East and alternative supply regions. By leveraging its strategic purchasing power and maintaining robust diplomatic ties with Moscow, Washington, and Gulf capitals, India has sought to secure waivers, favorable pricing terms, and uninterrupted delivery schedules. Indian energy firms are also accelerating investments in domestic renewable energy infrastructure—including solar, wind, and green hydrogen—to reduce long-term structural dependence on fossil fuel imports.
Islamabad has engaged in high-level diplomatic outreach with traditional allies in Riyadh and Abu Dhabi, seeking assurances regarding the continuity of petroleum supplies and the potential extension of financial support mechanisms. Simultaneously, Pakistani energy authorities are attempting to fast-track domestic exploration projects and improve energy efficiency standards. However, structural constraints mean that short-term fixes remain heavily dependent on external aid and geopolitical stability in the Gulf.
Dhaka has focused on diversifying its LNG procurement strategy, balancing long-term contracts with spot-market purchases while exploring potential energy cooperation frameworks with neighboring regional partners. The Bangladeshi government is also prioritizing the expansion of domestic renewable energy projects, recognizing that fossil fuel volatility poses an existential threat to its export-driven economic model.
Conclusion: The Imperative for Long-Term Energy Autonomy
The current disruption in the Middle East serves as a stark reminder to policymakers in New Delhi, Islamabad, Dhaka, and Kathmandu that reliance on volatile foreign energy corridors is an increasingly untenable growth strategy. While short-term diplomatic maneuvering and supply diversification can cushion immediate blows, the structural roots of the crisis demand a fundamental reimagining of South Asia’s energy architecture.
Accelerating the transition toward indigenous renewable energy sources, enhancing regional energy grids through cross-border electricity trade, and modernizing domestic extraction and distribution networks are no longer merely environmental objectives—they are absolute imperatives for national security and economic survival. Until these structural transformations are realized, the two billion residents of South Asia will remain tethered to the geopolitical winds and maritime security of the Persian Gulf, vulnerable to conflicts far beyond their borders.