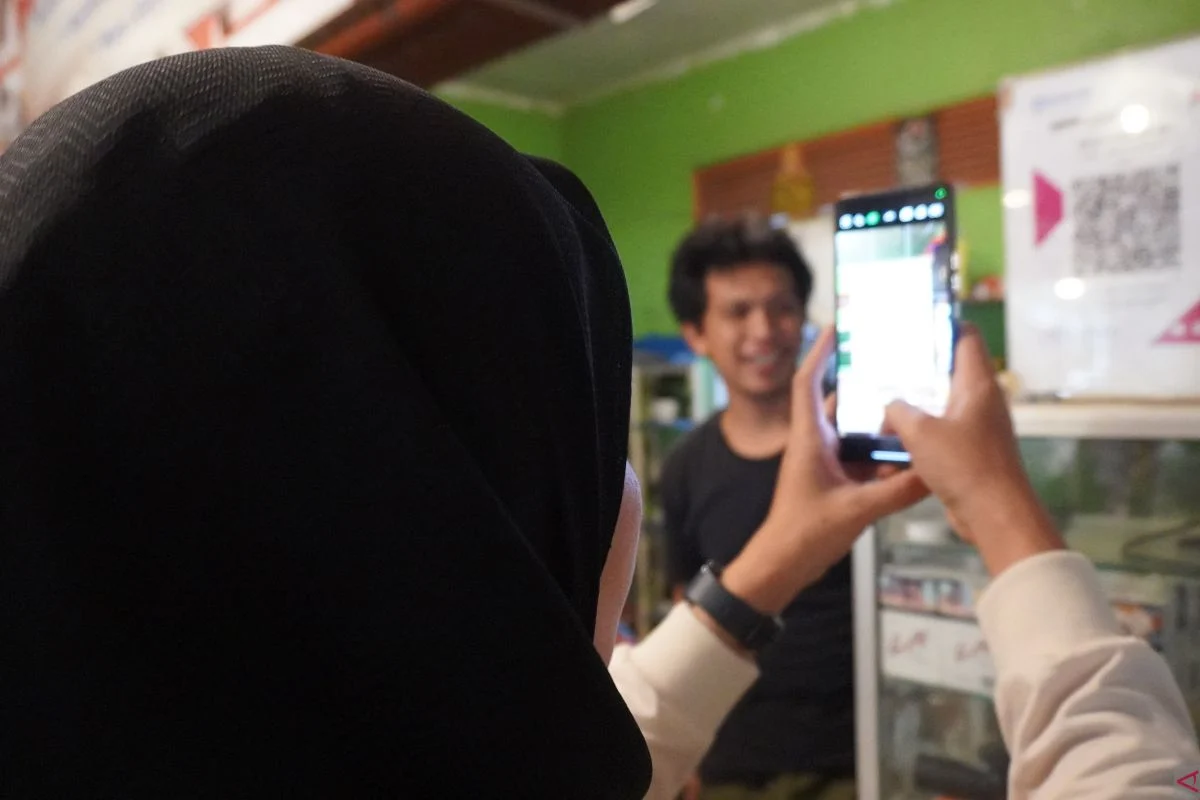
Jakarta has transformed into a bustling ecosystem of contactless transactions, where the traditional clink of loose change and the rustle of paper banknotes are rapidly being replaced by the soft chime of smartphone notifications. At the epicenter of this financial metamorphosis is Generation Z, a demographic of digital natives whose preference for speed, practicality, and efficiency has fundamentally altered the nation’s retail landscape. For Indonesia’s youth, carrying a physical wallet stuffed with cash is no longer a hallmark of preparedness; rather, it is viewed as an archaic inconvenience.
In its place, Quick Response Code Indonesian Standard, universally known as QRIS, has emerged as the undisputed king of daily transactions. Launched by Bank Indonesia, this standardized payment infrastructure has transcended its initial purpose as a mere utility tool to become an essential component of modern youth culture. From trendy coffee shops in South Jakarta to traditional street vendors in regional wet markets, QRIS has woven itself into the fabric of everyday life, accelerating Indonesia’s transition toward a comprehensive cashless society.
The Genesis and Evolution of Indonesia’s QR Code Standard
To understand the ubiquity of QRIS today, one must examine the fragmented digital payment landscape that preceded it. In the mid-2010s, Indonesia experienced an explosion of financial technology innovations. Multiple e-wallet providers entered the market, each deploying proprietary QR codes to capture market share. This fragmentation created significant friction for both consumers and merchants. Cashier counters at retail outlets were frequently cluttered with a chaotic array of acrylic stands, each displaying a different logo and a unique barcode for specific applications. Consumers were forced to check whether a particular merchant supported their preferred digital wallet before making a purchase.
Recognizing the inefficiencies of this siloed approach, Bank Indonesia, in collaboration with the Indonesian Payment System Association (ASPI), took a decisive step to unify the ecosystem. On August 17, 2019, QRIS was officially launched, establishing a single interoperable standard for QR code-based payments in the archipelago. The core philosophy behind QRIS was simple yet revolutionary: one standard, one QR code, for all applications.
Despite launching on the precipice of the global COVID-19 pandemic—a crisis that inadvertently served as a massive catalyst for digital adoption—QRIS experienced exponential growth. Regulatory backing, combined with an urgent public health need to minimize physical contact through shared cash, propelled the infrastructure forward. By the early 2020s, adoption rates had surged across micro, small, and medium enterprises (MSMEs), laying the groundwork for the tech-savvy generation of today to integrate the system seamlessly into their daily routines.
Why Generation Z Embraces the QRIS Lifestyle
The profound affinity between Generation Z and QRIS is rooted in the psychological and behavioral traits of individuals born roughly between 1997 and 2012. As true digital natives, this cohort values frictionless experiences. Several distinct factors explain why QRIS has captured the loyalty of young Indonesian consumers.
Unmatched Practicality and Speed
For Gen-Z, time is a highly valued commodity. Traditional cash transactions involve numerous micro-steps: handing over paper currency, waiting for the cashier to calculate the correct change, meticulously counting bills, and awkwardly stuffing coins back into a pocket or purse. These cumulative delays contradict the generation’s expectation of instant gratification.
With QRIS, the entire transaction process is compressed into a matter of seconds. A user simply unlocks their smartphone, opens their preferred mobile banking application or electronic wallet, taps the scanner icon, points the camera at the merchant’s QRIS code, inputs their secure PIN or biometric authorization, and receives an instant confirmation screen. This seamless workflow eliminates awkward delays at checkout lines and allows consumers to move rapidly through their day.
Universal Cross-Platform Compatibility
The interoperability of QRIS addresses the historical frustrations of fragmented digital finance. Because a single QRIS code can accept funds from virtually any participating financial institution or e-wallet provider, consumers are liberated from platform restrictions. A Gen-Z consumer using a digital wallet issued by a tech conglomerate can effortlessly pay a merchant whose settlement account is held at a traditional state-owned bank, using the exact same QR code displayed at the counter. This cross-platform flexibility aligns perfectly with the multi-app financial habits of young users, who often maintain accounts across several digital platforms to optimize rewards, cashback offers, and user interfaces.
Ubiquitous Accessibility Across All Merchant Tiers
The democratization of digital payments is another critical driver of adoption. In the past, advanced electronic payment methods such as credit cards were largely restricted to high-end department stores, hotels, and upscale restaurants, leaving everyday purchases in the cash-only domain. QRIS has dismantled this barrier. Today, the standardized black-and-white square code is ubiquitous. It can be found adorning high-end artisanal bakeries, sprawling music festivals, neighborhood convenience stores, mobile street-food carts, and traditional market stalls alike. This comprehensive market penetration ensures that young consumers can maintain a strict cashless lifestyle without experiencing the anxiety of encountering merchants who lack digital infrastructure.
Automated Financial Awareness and Tracking
Contrary to stereotypes depicting youth as reckless spenders, contemporary Generation Z exhibits a heightened consciousness regarding financial literacy and personal budgeting. Managing physical cash makes tracking cumulative expenses difficult, as unrecorded miscellaneous purchases gradually deplete wallets without a clear paper trail.
QRIS fundamentally transforms this dynamic through automated transaction logging. Every payment executed via the system is instantly recorded in the user’s digital application history, generating a comprehensive ledger of mutational data. This automatic categorization allows young professionals and students to review their daily spending habits, evaluate monthly budgets, and identify unnecessary expenditures without the tedious chore of manual bookkeeping. Consequently, the technology acts as an implicit tool for promoting financial wellness and disciplined money management.
Macroeconomic Implications and Institutional Perspectives
The explosive growth of QRIS is not merely a cultural phenomenon among consumers; it represents a fundamental structural shift in Indonesia’s national economy. Financial sector analysts and central bank authorities view the expansion of digital payments as a vital driver of economic formalization, financial inclusion, and transactional velocity.
Bank Indonesia has consistently reported robust transaction volumes across the archipelago, reflecting deep regional penetration extending far beyond major metropolitan centers like Jakarta. Furthermore, regulatory foresight has positioned QRIS for international scalability. Strategic initiatives are currently underway to explore cross-border QRIS connectivity with neighboring nations in Southeast Asia and beyond, potentially allowing Indonesian travelers—including tech-savvy young tourists—to make seamless retail payments abroad using the same familiar domestic infrastructure.
Industry stakeholders have similarly underscored the centrality of QRIS in their long-term growth projections. Major digital banking entities, such as BCA Digital, have repeatedly identified QRIS as the primary engine driving transaction volume growth. In corporate earnings outlooks and strategic disclosures, financial executives emphasize that QRIS serves as the foundational gateway that attracts young customers into the broader digital banking ecosystem, subsequently opening pathways for cross-selling complementary financial products such as micro-loans, digital savings accounts, and investment portfolios.
Economic analysts note that the widespread adoption of QRIS among MSMEs has yielded tangible benefits for small-scale merchants. By lowering the operational friction associated with handling physical cash—such as the risks of counterfeit currency, cash-handling errors, and the labor-intensive requirement of daily store reconciliations—merchants can operate with greater precision. Additionally, formalized digital transaction records enhance the credit-scoring profiles of micro-entrepreneurs, facilitating easier access to formal banking credit and working capital loans.
Looking Ahead: The Path to a Fully Cashless Society
As Generation Z matures and assumes greater economic purchasing power, their behavioral preferences will continue to shape the trajectory of Indonesia’s financial services sector. The convergence of instant connectivity, universal interoperability, and automated financial tracking has elevated QRIS from a temporary pandemic-era convenience into a permanent pillar of modern commerce.
The ongoing evolution of this digital payment ecosystem highlights a broader transformation within developing economies, where leapfrogging traditional legacy infrastructure—such as widespread credit card penetration—allows younger populations to adopt mobile-first financial habits directly. While physical cash will likely retain a residual role in specific niches for the foreseeable future, the systemic momentum established by QRIS ensures that Indonesia’s journey toward an inclusive, efficient, and technologically integrated cashless society is irreversible.