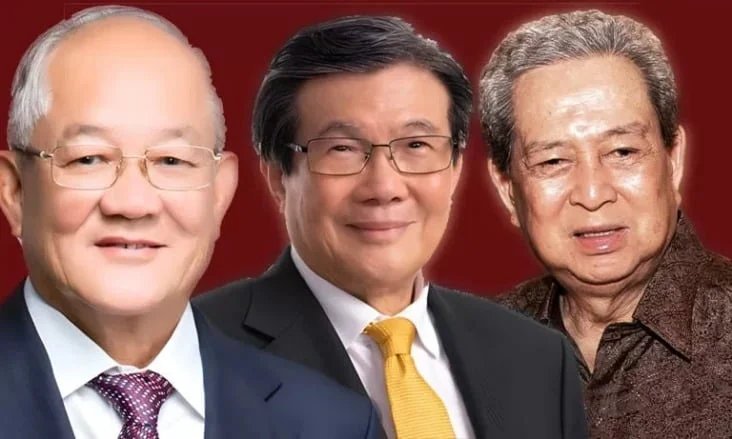
The Indonesian financial landscape is currently grappling with a profound correction that has effectively wiped out four years of wealth accumulation for the nation’s most prominent billionaires. According to data from the Bloomberg Billionaires Index as of October 22, 2026, the cumulative net worth of five of Indonesia’s top tycoons and their immediate families has plummeted by a staggering USD57 billion, equivalent to approximately IDR 1,033 trillion. This fiscal contraction follows a series of market signals triggered by MSCI Inc., which first signaled a potential downgrade of Indonesia’s equity market status in January 2026, creating a ripple effect that has shaken investor confidence and exposed the volatility inherent in concentrated ownership structures.
The Catalyst: The MSCI Warning and Market Sentiment
The downward trajectory of Indonesian equity valuations began in earnest following the announcement by MSCI Inc., a leading provider of critical decision-support tools and services for the global investment community. The warning regarding a potential reclassification of the Indonesian market—a move that would typically necessitate the rebalancing of institutional portfolios—sent shockwaves through the Jakarta Stock Exchange (IDX).
For international investors, an MSCI status downgrade acts as a red flag, often prompting automatic divestment from index-tracking funds. The prospect of such a downgrade intensified capital outflows, as global asset managers sought to de-risk their portfolios ahead of any formal policy change. By October 2026, the Indonesia Composite Index (IHSG) had recorded a year-to-date decline of 38%, marking it as the worst-performing benchmark among more than 90 indices monitored globally by Bloomberg.
Chronology of the Wealth Erosion
The financial deterioration of Indonesia’s business elite did not occur in a vacuum. It was the culmination of a ten-month period characterized by heightened regulatory scrutiny, shifting global macroeconomic conditions, and specific corporate governance challenges.
- January 2026: MSCI Inc. issues its first warning regarding Indonesia’s equity market status, citing concerns over liquidity, market accessibility, and transparency.
- Q1-Q2 2026: Initial volatility leads to a steady decline in major blue-chip stocks, particularly those in the energy and banking sectors, which hold the highest weighting in the IHSG.
- August 2026: Market sentiment worsens as domestic political discourse touches upon foreign investment protections, leading to increased caution among institutional investors.
- October 2026: The situation reaches a critical juncture when major stakeholders, including energy magnate Low Tuck Kwong, execute significant equity divestments. The resulting fire-sale pricing—often at deep discounts to previous closing prices—further depressed market valuations, leading to the current USD57 billion loss estimate.
Profiles of the Affected Tycoons
The concentration of wealth in Indonesia is heavily tied to a handful of conglomerate structures where family control remains paramount. The current market downturn has disproportionately affected these individuals.
Prajogo Pangestu: The Petrochemical Pivot
Prajogo Pangestu, the founder of Barito Pacific, has faced the most significant financial hit in absolute terms. Since the initial warning in January, his net worth has cratered by more than 60%. Despite the decline, he remains the second-wealthiest person in Indonesia with a net worth of approximately USD15 billion. His wealth is deeply tied to the petrochemical and energy sectors, which have been particularly sensitive to the overall downturn in Indonesian industrial output and investor appetite for emerging market cyclicals.
The Hartono Dynasty: BCA and Djarum Group
Budi Hartono, the principal shareholder of the Djarum Group and a cornerstone investor in Bank Central Asia (BCA), has seen his fortune shrink by over USD5 billion, a 31% reduction. His family members, who collectively hold stakes in various sectors ranging from telecommunications to electronics, have suffered a similar fate, losing an additional USD5 billion. The decline in BCA’s share price is particularly noteworthy, as the bank is often viewed as a proxy for the health of the Indonesian economy.
Low Tuck Kwong: The Energy Sector Correction
The coal magnate Low Tuck Kwong has experienced a 54% reduction in his net worth, leaving him with roughly USD10 billion. This decline is largely attributed to a strategic but damaging exit from Bayan Resources. Earlier this month, Low and his daughter divested approximately 30% of their stake in the company. The transaction, executed at prices 80% below the previous day’s closing, served as a catalyst for a broader sell-off, highlighting the liquidity risks associated with large, founder-led firms when market confidence is low.
Financial Analysis: The "Paper Wealth" Paradox
Layenda Kresna Bramanta, a finance lecturer at the Deakin-Lancaster Indonesia campus, notes that the loss is primarily a reflection of market pricing rather than a fundamental collapse in physical asset values. "Most of this wealth is on paper," Bramanta stated. "The massive decline reflects the high sensitivity of controlling stakes in large companies to market sentiment. In Indonesia, where ownership is highly concentrated, a lack of market depth means that even modest selling pressure can lead to massive fluctuations in valuation."
The analysis suggests that the current crisis is exacerbated by "ownership concentration risk." When founders or controlling families hold a significant portion of a company’s shares, the public float is often smaller. While this provides stability during bull markets, it creates extreme volatility during periods of divestment or institutional panic, as seen throughout 2026.
The Government and Official Response
The Indonesian government, led by President Prabowo, has remained defiant in the face of these market pressures. Recognizing the potential for the MSCI warning to turn into a self-fulfilling prophecy, the President issued a direct message to the global investment community, stating, "Indonesia is not afraid of anyone," and emphasizing that the nation’s economic fundamentals remain sound despite the current equity market volatility.
Government officials argue that the stock market performance does not reflect the underlying growth of the real economy. They point to steady GDP growth figures, infrastructure development, and ongoing fiscal discipline as evidence that the "MSCI factor" is a technical market issue rather than a structural economic failure. Nevertheless, the disconnect between government rhetoric and investor behavior remains a point of contention for market analysts.
Broader Implications for the Indonesian Economy
The erosion of USD57 billion in wealth has several critical implications for Indonesia’s economic trajectory:
- Capital Expenditure Constraints: Many of the tycoons affected are the primary drivers of private sector capital expenditure. A significant reduction in their net worth—and the accompanying loss of access to cheap capital markets—may lead to the delay or cancellation of major infrastructure and industrial projects.
- Banking Sector Stability: With prominent figures like the Hartonos having significant exposure to the banking sector, the volatility could create secondary pressures on bank capital adequacy if those shares are pledged as collateral for loans.
- Investment Climate Reform: The situation has reignited calls for deeper capital market reforms, including efforts to increase the number of independent board members in listed companies, improve transparency in share pledging, and broaden the investor base to reduce reliance on a few dominant shareholders.
- Foreign Direct Investment (FDI) vs. Portfolio Flows: While the equity market (portfolio investment) is suffering, the government is attempting to pivot focus toward attracting more sustainable, long-term FDI. The hope is that by de-emphasizing the volatility of the stock market, the nation can attract institutional investors interested in real-world assets rather than short-term speculative positions.
Conclusion
The events of 2026 serve as a stark reminder of the risks associated with the integration of emerging markets into the global financial system. The warnings from MSCI Inc. acted as a trigger for a deeper, latent anxiety regarding market liquidity and governance. As the Indonesian authorities navigate the remainder of the year, the focus will likely shift toward restoring investor confidence through improved market accessibility and a clear commitment to corporate transparency. For now, the nation’s wealthiest individuals remain the most visible casualties of a market that is rapidly recalibrating its expectations in an increasingly uncertain global financial environment. The "lost years" of wealth accumulation serve as a cautionary tale for both policymakers and investors in emerging economies, underscoring the vital need for a more diverse, liquid, and transparent capital market ecosystem.