The Government of Indonesia has officially announced the complete settlement of all sovereign debt instruments issued to rescue the domestic financial and banking sectors during the devastating 1997-1998 Asian Financial Crisis. This historic milestone, finalized in August 2026, marks the conclusion of a nearly three-decade fiscal recovery journey that reshaped the nation’s macroeconomic architecture, regulatory frameworks, and sovereign debt management policies.
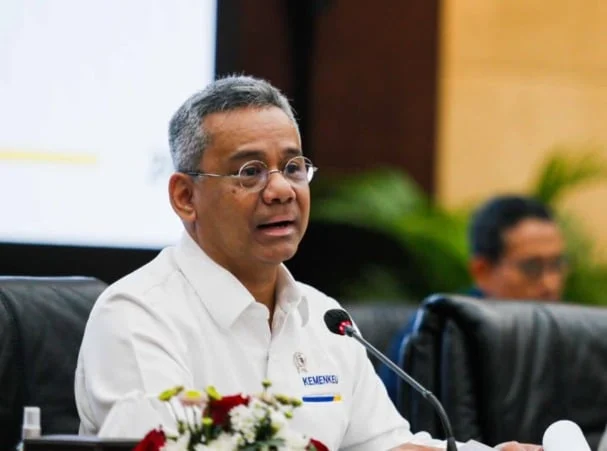
The announcement was made public by Deputy Finance Minister Suahasil Nazara during the State Budget (APBN KiTa) press conference held on Friday, September 18, 2026. According to the Ministry of Finance, the total nominal value of the bonds issued during the peak of the crisis reached an astronomical Rp640 trillion. The complete extinguishment of these legacy liabilities signifies a monumental closure to one of the darkest chapters in modern Indonesian economic history, paving the way for enhanced fiscal autonomy and renewed international confidence in the country’s sovereign creditworthiness.
Chronology of the Crisis and Legacy Debt Issuance
The origins of the Rp640 trillion debt burden trace back to the onset of the Asian Financial Crisis in mid-1997. What began as a currency contagion originating in Thailand rapidly metastasized across Southeast Asia, severely impacting Indonesia. The Indonesian rupiah plummeted from approximately Rp2,500 per US dollar to over Rp15,000 per US dollar at the height of the panic in 1998.
The collapse of the exchange rate triggered widespread corporate insolvencies, a massive liquidity crunch, and a devastating run on domestic commercial banks. To prevent the complete systemic collapse of the financial architecture, the Indonesian government, in coordination with international financial institutions such as the International Monetary Fund (IMF), stepped in as the guarantor of the banking system.
Under the framework of the master restructuring and rescue operations, the government injected massive liquidity into ailing financial institutions and assumed control of distressed assets. To fund these emergency interventions, the state issued specialized government bonds. These instruments were broadly categorized into two major types: recapitalization bonds (obligasi rekapitulasi) issued to shore up the capital adequacy ratios of struggling banks, and specialized sovereign notes tied to the management and resolution of liquidity support mechanisms, notably the Bank Indonesia Liquidity Assistance (BLBI).
Phased Amortization Over Nearly Three Decades
The retirement of the Rp640 trillion crisis debt portfolio was deliberately structured as a long-term, multi-decade fiscal operation designed to avoid destabilizing the national budget or triggering inflationary pressures. Ministry of Finance data indicates that the amortization process was executed in distinct chronological phases.
The initial phase of relief focused on the retirement of specific tranches of bank recapitalization bonds, which were progressively paid down as the domestic banking sector regained profitability and the government successfully privatized or liquidated nationalized banks. By July 2020, the government had successfully settled the entirety of the recapitalization bond obligations.
However, the longer-term liabilities—specifically those associated with complex asset recovery programs and BLBI-related sovereign instruments—required a more protracted resolution timeline. These residual obligations remained active on the state balance sheet through the early 2020s, undergoing continuous restructuring, liability management operations, and scheduled redemptions. The final vestige of these crisis-era debt instruments was officially retired in August 2026, bringing a definitive end to the nearly 30-year amortization cycle.
Funding Mechanisms and the Role of Bank Indonesia Surpluses
The systematic liquidation of the crisis-era debt was made possible through prudent fiscal management and specific statutory mechanisms governing the transfer of central bank profits. According to Deputy Finance Minister Suahasil Nazara, the final payments utilized accumulated fiscal buffers and statutory transfers of surplus capital from Bank Indonesia (BI) to the state general treasury, in strict compliance with prevailing legislative mandates.
Under Indonesian law, a portion of the operational surpluses generated by the central bank can be channeled toward sovereign debt reduction and the enhancement of government cash reserves. This institutional synergy between fiscal authority (the Ministry of Finance) and monetary authority (Bank Indonesia) proved vital in ensuring that the monumental debt burden was serviced and ultimately extinguished without compromising the government’s capacity to finance ongoing public infrastructure projects, social safety nets, and human capital development programs.
Macroeconomic Implications and Sovereign Credit Rating Impacts
Financial analysts and macroeconomic observers have lauded the complete settlement of the 1997-1998 crisis debt as a watershed moment for Indonesia’s sovereign risk profile. For decades, the legacy bonds represented a structural rigidity in the state budget, necessitating continuous interest payments and debt-servicing allocations that could have otherwise been deployed toward productive capital expenditures.
With these legacy liabilities entirely removed from the sovereign balance sheet, the Indonesian government enjoys unprecedented fiscal headroom. This development is expected to favorably influence international credit rating agencies—such as Moody’s, S&P Global, and Fitch Ratings—by further demonstrating Indonesia’s unwavering commitment to fiscal discipline, debt sustainability, and macroeconomic stability.
Furthermore, the closure of the crisis-era debt cycle enhances investor sentiment. Global institutional investors closely monitor a country’s debt vintage and historical default or restructuring records. By cleanly resolving the financial obligations stemming from its most severe historical crisis, Indonesia reinforces its reputation as a reliable sovereign borrower with a pristine track record of honoring long-term financial commitments.
Historical Context and Structural Reforms
Economists point out that while the financial cost of the 1997-1998 crisis was immense, the structural reforms forced upon the nation served as the foundation for Indonesia’s modern economic resilience. In the wake of the crisis, sweeping institutional overhauls were implemented. These included the enactment of the central bank independence law, the establishment of the Deposit Insurance Corporation (LPS) to protect depositor funds without requiring ad-hoc state bailouts, and the creation of the Financial Services Authority (OJK) to provide integrated supervision of the banking and capital markets.
The rigorous fiscal rules codified in the aftermath of the crisis—such as the statutory limit capping the annual budget deficit at 3 percent of Gross Domestic Product (GDP) and total public debt below 60 percent of GDP—ensured that successive administrations maintained budgetary restraint while systematically paying down the Rp640 trillion rescue bill.
Looking Forward: A New Chapter in Fiscal Independence
As Indonesia enters the post-crisis debt era, the focus of fiscal policy is pivoting toward structural transformation, green energy transition, and digital economy enablement. Government officials have emphasized that the financial resources previously earmarked for legacy debt servicing can now be reallocated toward high-multiplier investments, including downstream processing of natural resources, universal healthcare expansion, and comprehensive educational reforms.
The definitive clearance of the 1997-1998 rescue obligations stands as a testament to the resilience of Indonesia’s state finances. It closes a chapter defined by emergency survival and opens a new era characterized by fiscal maturity, strategic autonomy, and sustainable long-term economic development.
