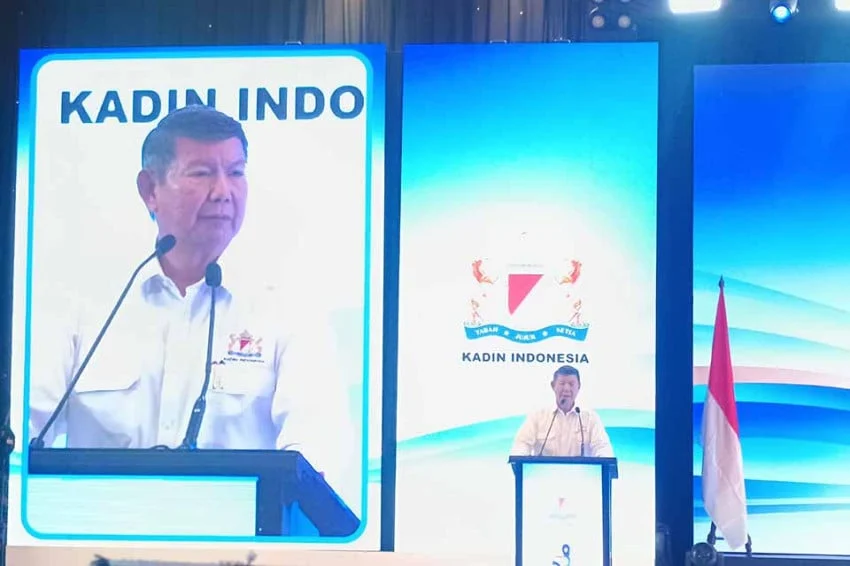
The Indonesian economy is currently facing a critical juncture as high-level concerns emerge regarding the stability of the national currency. Hashim Djojohadikusumo, the Special Envoy of the President for Climate and Energy and a prominent member of the Kadin Advisory Board, has issued a stark warning that the Indonesian rupiah could face a severe devaluation, potentially reaching the level of Rp21,000 per US dollar. This alarming projection comes amidst growing anxiety over the potential reclassification of the Indonesian capital market by Morgan Stanley Capital International (MSCI).
The warning, delivered during the Kadin National Leadership Meeting (Rapimnas) in Jakarta on Thursday, October 29, 2026, highlights a systemic risk: the mass exodus of foreign capital. Such an outflow would be triggered if global index providers downgrade Indonesia’s market status to a "standalone market," a move that would effectively isolate Indonesian equities from the portfolios of global institutional investors.
The MSCI Catalyst and Market Credibility
At the heart of this financial uncertainty is the scrutiny from global index providers, specifically MSCI. The organization has raised significant concerns regarding the structural integrity of the Indonesian stock market. Specifically, international analysts have pointed to a lack of liquidity, constrained free-float percentages—the portion of shares held by public investors—and what they describe as "irrational" Price-to-Earnings (P/E) ratios among certain listed companies.
When global investors perceive that a market is disconnected from its fundamental value, they naturally seek safer havens. A reclassification by MSCI would force passive investment funds—which track these indices—to automatically divest from Indonesian stocks. The resulting sudden sell-off would exert immense downward pressure on the rupiah as foreign investors convert their assets back into US dollars, exacerbating the currency’s vulnerability.
Understanding the Mechanics of the Potential Collapse
Hashim’s assessment is not based on mere speculation but on the correlation between capital market health and currency stability. When foreign capital flees the stock market, the demand for the rupiah diminishes, while the demand for the US dollar surges.
"I have calculated the risks, and if the investment flows out of our stock market, the rupiah could weaken significantly to the range of Rp20,000 to Rp21,000, and some estimates even suggest Rp22,000," Hashim stated during the Rapimnas.
The mechanism is straightforward: Indonesia remains a net importer of capital. A sudden reversal of this flow creates an immediate balance-of-payments challenge. If the central bank, Bank Indonesia, lacks sufficient reserves to intervene effectively against such a large-scale exodus, the currency depreciation becomes difficult to arrest.
The Issue of Market Manipulation and "Stock Frying"
A critical component of this crisis is the integrity of the domestic market. Hashim explicitly alluded to the existence of "unhealthy practices" within the Indonesia Stock Exchange (IDX), colloquially referred to as "saham gorengan" or "fried stocks." These are assets whose prices are manipulated through artificial trading volumes and coordinated buying, which do not reflect the actual financial performance or the underlying assets of the companies.
"There are clear indications of unhealthy practices occurring in our stock market. I do not need to name names, but there are stocks that are being ‘fried’—artificially inflated," Hashim added.
This manipulation damages the credibility of the Indonesian market on the international stage. Global investors rely on transparency and efficient price discovery; when these are absent, the risk premium for investing in Indonesia rises. If foreign capital perceives that the market is rigged, the cost of capital for all Indonesian companies increases, and the likelihood of a massive exit—as warned by Hashim—becomes a statistical probability rather than a remote risk.
Chronology and Context: The Path to Current Vulnerability
The current threat to the rupiah does not exist in a vacuum. It is the culmination of several economic factors that have been brewing over the past two years:
- Mid-2025: Initial concerns were raised by international rating agencies regarding the widening gap between the growth of domestic indices and the stagnant earnings growth of listed companies.
- Early 2026: MSCI began conducting a formal review of Indonesia’s market accessibility, noting the low free-float requirements of several major Indonesian conglomerates.
- August 2026: The rupiah experienced significant volatility, testing the psychological barrier of Rp18,000 per US dollar, prompting Bank Indonesia to implement emergency stabilization measures.
- October 2026: The Kadin Rapimnas serves as the platform for the government to acknowledge that the situation has escalated from a market accessibility issue to a national security issue.
The Debt Trap and Economic Implications
The implications of a move toward Rp22,000 per US dollar are dire. Indonesia holds significant external debt denominated in foreign currencies, both at the sovereign and corporate levels. A devaluation of this magnitude would lead to a "debt ballooning" effect. Companies that earn in rupiah but owe in dollars would see their debt-servicing costs effectively double.
During the Rapimnas, Hashim emphasized this point to stakeholders, including Chairman of the Lippo Group James Riady and Minister of Investment Rosan Perkasa Roeslani. The logic is clear: if the currency loses value against the dollar, the cost of importing capital goods, energy, and raw materials will skyrocket, fueling domestic inflation. This, in turn, would squeeze household purchasing power and potentially lead to an economic contraction, creating a vicious cycle of further capital flight and currency depreciation.
Official Responses and Government Strategy
The government is not standing idly by. Discussions between Hashim Djojohadikusumo and the newly empowered Danantara (the government’s sovereign wealth management entity led by Rosan Roeslani) indicate that a coordinated strategy is being formulated.
The focus appears to be two-fold:
- Regulatory Enforcement: Strengthening the surveillance of the Indonesia Stock Exchange to curb the practice of price manipulation. This includes stricter enforcement of free-float requirements and more transparent disclosure standards for listed companies.
- Market Stabilization: Utilizing Danantara’s resources to provide liquidity support and restore investor confidence, ensuring that the market is seen as a transparent and viable place for long-term investment.
However, analysts suggest that domestic measures alone may not be enough. Restoring investor confidence requires a clear commitment to structural reform. If the government can demonstrate a credible plan to address the "P/E ratio anomalies" and enforce fair-play regulations, it may be able to persuade MSCI to maintain Indonesia’s current status.
Broader Economic Analysis
The warning from the President’s Special Envoy highlights a profound structural vulnerability in the Indonesian economy: its reliance on foreign portfolio investment to maintain currency stability. While Indonesia has made significant strides in direct investment (FDI), the volatility of "hot money" in the stock market remains a persistent Achilles’ heel.
The "standalone market" designation would be a significant blow to the prestige and competitiveness of the Indonesian financial system. It would effectively mark Indonesia as a "frontier" market, significantly increasing the cost of capital for domestic firms seeking to raise funds internationally.
Conclusion: A Call for Reform
The warning issued by Hashim Djojohadikusumo should be viewed as a wake-up call for both the private sector and the regulators. The integrity of the stock market is no longer just a matter of finance; it is a matter of national economic stability.
If Indonesia wishes to avoid the catastrophic scenario of a currency collapse to Rp21,000 or beyond, it must move rapidly to align its capital market practices with international standards. This requires more than just rhetoric; it requires the bold enforcement of laws against market manipulation, a commitment to increasing the free-float of major issuers, and a transparent approach to corporate governance.
As of late 2026, the window to prevent a full-scale market reclassification is closing. The actions taken by the government and the IDX in the coming months will be critical in determining whether Indonesia remains an attractive destination for global capital or faces a period of intense economic volatility that could reset the country’s growth trajectory for years to come.
