Jakarta, September 14, 2026 – As the automotive landscape continues to expand across major urban centers in Indonesia, the necessity of securing adequate vehicular protection has become a paramount concern for car owners. Selecting the right insurance policy serves as a vital financial buffer against the unpredictable costs associated with vehicular damage, accidents, or total loss through theft. Despite the growing penetration of insurance products in the country, a significant portion of vehicle owners remain hesitant or uninformed regarding the fundamental distinctions between comprehensive protection—commonly referred to as "All Risk"—and Total Loss Only (TLO) policies.
Understanding these differences is not merely a matter of administrative compliance; it represents a critical financial decision that dictates out-of-pocket expenses when unexpected road incidents occur. Industry stakeholders, insurance providers, and insurtech platforms are increasingly emphasizing the need for consumer education to bridge this knowledge gap, ensuring that policyholders acquire coverage that accurately mirrors their driving habits, vehicle valuation, and risk exposure.
Comprehensive Breakdown of All Risk Insurance Coverage
To the uninitiated, the term "All Risk" implies an absolute blanket of protection where every conceivable mishap involving a vehicle is seamlessly covered by the underwriting insurance company. However, insurance experts consistently remind consumers that this terminology is somewhat of a misnomer. While All Risk insurance—technically categorized as comprehensive coverage—offers a significantly broader spectrum of protection compared to its counterparts, it is still governed by specific policy clauses, exclusions, and deductibles.
Under a standard All Risk policy, vehicle owners are safeguarded against a wide array of incidents. This includes major collisions, rollovers, acts of vandalism, fire damage, and even minor cosmetic grievances such as door dings, bumper scrapes, and body panel scratches. For vehicle owners navigating congested metropolitan areas like Jakarta, where minor fender-benders and parking lot scrapes are a daily occurrence, All Risk coverage provides immense peace of mind. The ability to claim repair costs for minor aesthetic damages makes this option particularly attractive for owners of brand-new vehicles or luxury cars, where replacement parts and specialized paint jobs can incur exorbitant bills.
Nevertheless, policyholders must meticulously review the fine print of their contracts. Certain conditions are universally excluded from All Risk policies. Typical exclusions involve damages sustained while the driver is operating the vehicle under the influence of alcohol or narcotics, engaging in illegal street racing, driving without a valid driver’s license, or utilizing the car for unauthorized commercial transport purposes like unauthorized ride-hailing. Furthermore, intentional damage caused by the insured party or losses resulting from war, civil unrest, and nuclear hazards are strictly barred from coverage. Thus, while All Risk delivers extensive protection, it demands responsible vehicle operation to remain valid.
Decoding Total Loss Only (TLO) Protection
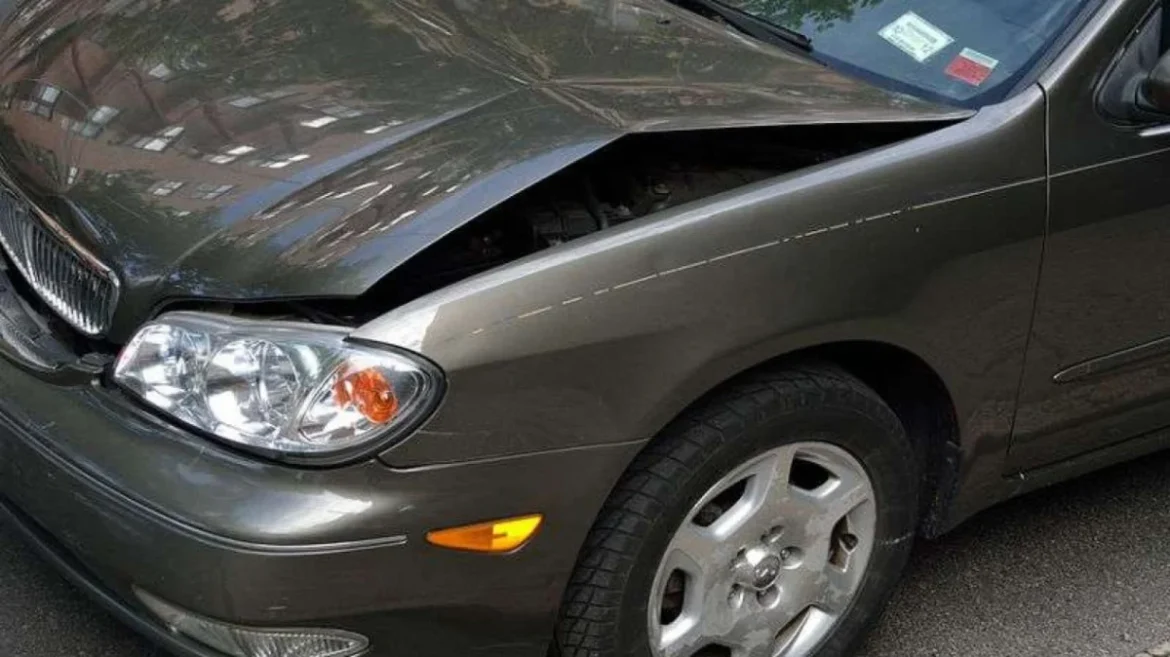
In stark contrast to comprehensive policies, Total Loss Only (TLO) insurance is engineered with a much narrower scope of coverage. As the nomenclature suggests, TLO policies do not cater to minor repairs or cosmetic blemishes. A policyholder cannot file a claim for a scratched bumper, a cracked side mirror, or a minor dent sustained while navigating a tight alleyway.
Instead, TLO coverage is strictly activated under two primary conditions: first, when the vehicle suffers catastrophic physical damage where the estimated cost of repairs reaches or exceeds a specific threshold—typically stipulated as 75 percent or more of the vehicle’s actual market value at the time of the incident, as outlined in the policy terms. Second, TLO policies provide critical financial indemnification in the unfortunate event that the insured vehicle is stolen through grand theft auto or armed robbery.
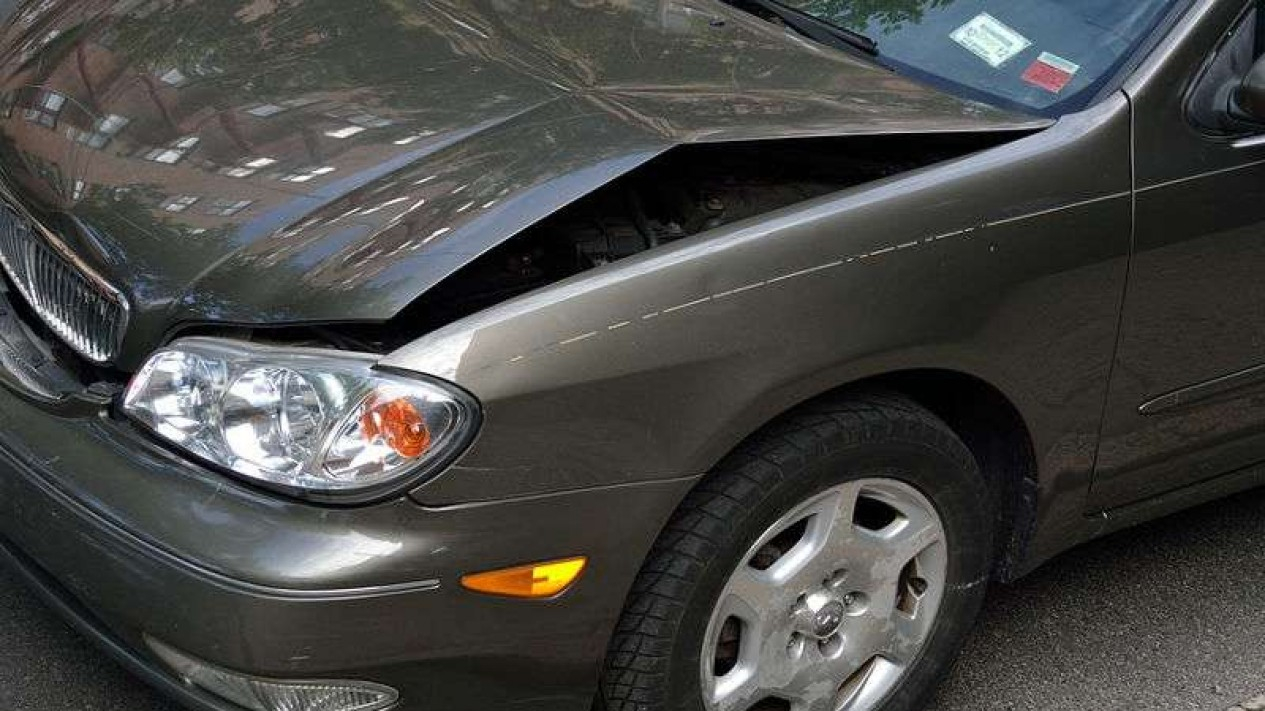
Because of this targeted threshold, TLO premiums are structurally more affordable, making it a popular choice for owners of older vehicles, drivers operating cars with depreciated market values, or individuals seeking basic financial defense against catastrophic loss without paying the higher premiums associated with comprehensive coverage. The underlying economic logic is straightforward: for an older car valued at a fraction of its original purchase price, paying for an All Risk policy may yield diminishing returns, whereas a TLO policy ensures that a total write-off or vehicle theft will not result in total financial devastation.
The Financial Equation: Premium Structures and Cost-Benefit Analysis
The divergence in coverage scope between All Risk and Total Loss Only naturally translates into a distinct discrepancy in pricing structures. Insurance companies in Indonesia calculate premiums based on a multitude of risk variables, including the vehicle’s make, model, manufacturing year, geographic risk zone, and the chosen type of coverage.
All Risk insurance commands a higher premium because the insurer assumes a vastly higher frequency of risk exposure. Paying out numerous small claims for minor dents and scratches throughout a policy year accumulates significant administrative and repair costs for the insurance provider. Conversely, TLO insurance features considerably lower premiums precisely because the insurer’s liability is legally restricted to extreme scenarios—either complete destruction or total disappearance of the asset.
Financial planners and insurance advisors frequently recommend evaluating the age and usage profile of the automobile before committing capital to a specific policy. For instance, a brand-new vehicle rolling off the dealership floor is a prime candidate for All Risk insurance during its first few years of operation, given its high replacement value and the emotional weight of maintaining pristine conditions. Conversely, a vehicle that has crossed the five-year mark, or one primarily utilized for rugged commutes in high-risk traffic environments where minor cosmetic damage is inevitable, might see a more rational cost-benefit balance under a TLO framework.
Industry Perspectives on Consumer Awareness and Digital Transformation
Addressing the persistent knowledge gap among Indonesian motorists, Juanri, the Vice President of Insurance at Cermati Protect, emphasized the critical importance of consumer education in the modern insurance ecosystem. According to industry observations, many vehicle owners purchase policies based solely on the cheapest available price, only to discover during a critical moment of need that their specific type of damage is excluded or falls outside the scope of their chosen coverage tier.
"We are firmly committed to streamlining the process for the general public, making it significantly easier for individuals to acquire accurate information and select car insurance products that genuinely align with their unique requirements and financial realities," Juanri stated on Monday, September 14, 2026. He highlighted that informed consumers are better equipped to protect their assets without suffering from under-insurance or paying for redundant coverage features.
The evolution of the insurtech sector in Indonesia has played a transformative role in democratizing access to insurance products. Platforms such as Cermati Protect have shifted the paradigm from traditional, agent-heavy paperwork processes to seamless, transparent online procurement channels. Through digital interfaces, prospective policyholders can instantly compare the nuances of All Risk and TLO policies, analyze coverage limits, review partner insurer networks, and customize their deductible options directly from their mobile devices or desktop computers.
The Role of Strategic Partnerships in Modern Insurtech Ecosystems

The modern landscape of digital insurance distribution relies heavily on robust institutional partnerships to maintain consumer trust and operational credibility. Leading digital platforms do not operate in a vacuum; they bridge the gap between individual consumers and established, licensed financial institutions.
Cermati Protect, for instance, operates an extensive digital ecosystem supported by strategic alliances with more than ten reputable general insurance companies officially registered and regulated by the Financial Services Authority (OJK) of Indonesia. This collaborative framework ensures that regardless of whether a customer opts for a comprehensive All Risk policy or a budget-friendly TLO plan, the underlying backing is anchored by financially stable underwriters capable of honoring valid claims promptly.
Furthermore, industry recognition serves as a benchmark for service excellence in an increasingly competitive market. Cermati Protect’s recent achievement of securing the prestigious Service Quality Award 2026 within the "Car Insurance Online Purchase Service Experience" category underscores the growing consumer demand for frictionless, digital-first insurance journeys. As customer expectations shift toward instant policy issuance, transparent claims assistance, and accessible customer support, digital aggregators are compelled to maintain rigorous service standards across their entire operational footprint.
Broader Economic Implications and Future Outlook for the Indonesian Insurance Market
The broader economic implications of vehicular insurance adoption extend far beyond individual vehicle protection. As Indonesia’s middle class continues to expand, accompanied by rising automotive sales and vehicle ownership rates across major urban hubs like Jakarta, Surabaya, Bandung, and Medan, the exposure to traffic-related financial liabilities grows proportionally.
Uninsured or under-insured motorists involved in major traffic accidents frequently face crippling financial burdens, which can cascade into broader economic distress for households. By fostering a deeper understanding of insurance mechanics—specifically the functional differences between All Risk and TLO policies—industry stakeholders contribute to a more financially resilient society. Increased insurance literacy encourages responsible asset management and mitigates the macroeconomic shocks of vehicular loss.
Looking ahead, the convergence of digital technology and traditional insurance underwriting is projected to accelerate further. Insurtech firms are anticipated to integrate artificial intelligence, data analytics, and telematics to offer hyper-personalized insurance premiums based on actual driving behavior rather than generalized risk pools. However, foundational education regarding policy types will remain the cornerstone of consumer empowerment.
Ultimately, whether a car owner opts for the expansive safety net of an All Risk policy or the targeted defense of a Total Loss Only plan, the definitive key to successful insurance utilization lies in proactive research, accurate asset valuation, and a clear comprehension of policy terms. As digital platforms continue to dismantle traditional barriers to entry, Indonesian motorists possess unprecedented access to the tools and information necessary to safeguard their vehicular investments effectively against the uncertainties of the road.
