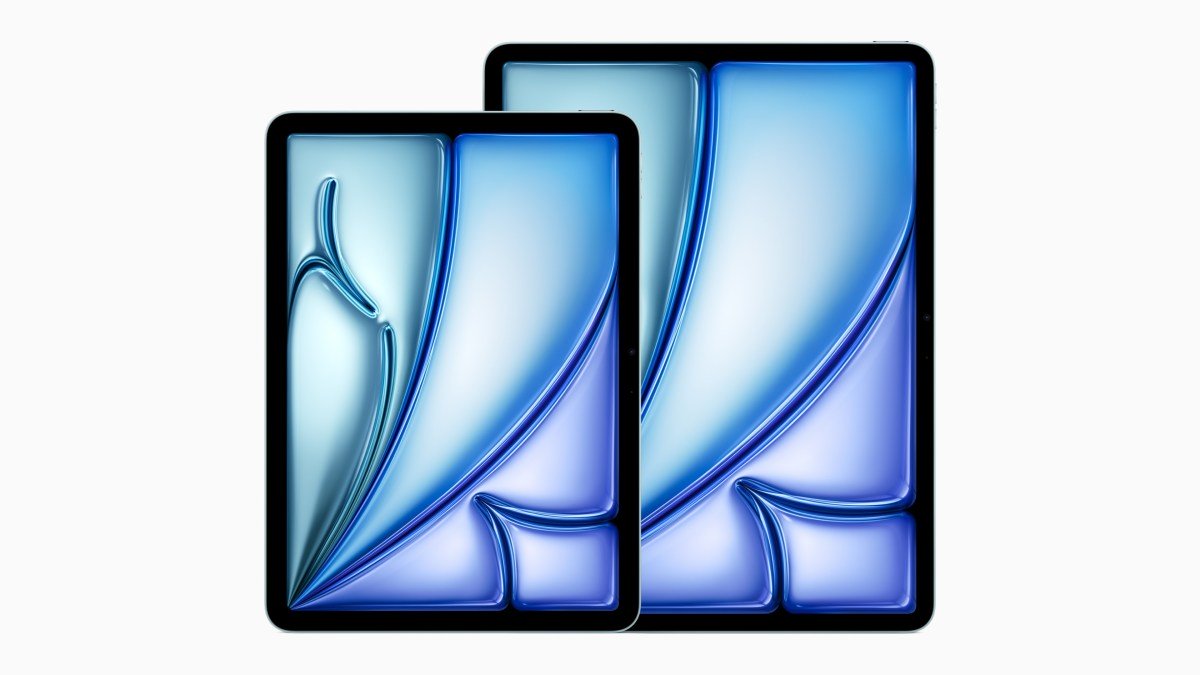
Apple Inc. is reportedly orchestrating a significant shift in its tablet hardware strategy, with industry supply chain reports indicating that Samsung Display is poised to become the dominant supplier of OLED panels for the next generation of iPad Air models. Expected to debut in the first half of 2027, this transition marks a pivotal moment in Apple’s ongoing efforts to standardize high-contrast, energy-efficient display technology across its premium and mid-range tablet portfolios. According to industry analysts, Apple is preparing for two distinct screen sizes—11 inches and 13 inches—with an projected demand of approximately 4 million to 5 million units for the initial launch window. While Samsung Display is currently positioned to capture the lion’s share of this procurement, China-based manufacturer BOE Technology Group is also aggressively pursuing a foothold in the supply chain, contingent upon meeting Apple’s rigorous quality control benchmarks.
The Strategic Shift Toward OLED Standardization
The move to adopt OLED (Organic Light-Emitting Diode) technology for the iPad Air line is part of a broader, multi-year roadmap by Apple to phase out traditional Liquid Crystal Display (LCD) technology in its higher-tier tablets. Unlike LCDs, which rely on a static backlight layer, OLED panels utilize self-emissive pixels that provide superior contrast ratios, deeper blacks, and improved color accuracy.
For the end-user, this transition represents a substantial upgrade in visual fidelity. The expected move to OLED aligns the iPad Air more closely with the visual experience currently offered by the iPad Pro series. However, Apple is reportedly maintaining a clear technological distinction between the two product tiers. While the high-end iPad Pro utilizes a sophisticated "tandem" OLED structure—combining two layers of organic material for enhanced brightness and longevity—the upcoming iPad Air is expected to feature a "single-stack" OLED configuration. This decision is viewed by industry observers as a calculated cost-optimization strategy, allowing Apple to deliver the benefits of OLED without the significantly higher manufacturing costs associated with the tandem technology found in the professional-grade models.
Supply Chain Dynamics and Market Competition
The competitive landscape for display manufacturing remains intense. Samsung Display, having already solidified its status as a trusted partner for Apple’s iPhone and high-end iPad Pro displays, remains the clear frontrunner for the iPad Air contract. Its established capacity to scale production of LTPS (Low-Temperature Polycrystalline Silicon) OLED panels makes it the most viable partner for a project of this magnitude.
BOE, meanwhile, is strategically positioning its B12 facility in Chongqing, China, to meet the stringent requirements of the Apple supply chain. The B12 plant, which specializes in Gen-6 OLED production, is the centerpiece of BOE’s aspirations to challenge the dominance of South Korean manufacturers. However, the path to becoming an Apple supplier is notoriously difficult. Before securing a commercial production order, BOE must navigate a rigorous vetting process that includes multiple rounds of sample submission and stress testing. Analysts note that even if BOE successfully qualifies as a secondary supplier, its initial contribution to the 2027 iPad Air launch is likely to be marginal compared to the massive output expected from Samsung Display.
Projected Supply Chain Chronology
The following timeline summarizes the expected trajectory of this display transition:
- Late 2025 – Early 2026: Initial procurement planning and finalized design specifications for the 2027 iPad Air series.
- Mid-2026: Evaluation of panel samples from various suppliers, including critical quality testing for BOE’s B12 facility.
- Late 2026: Finalization of production quotas for Samsung Display and potential secondary suppliers.
- First Half 2027: Anticipated global launch of the new iPad Air models featuring OLED technology.
- Full Year 2027: Targeted production volume of 4 to 5 million units, contingent upon consumer demand and market conditions.
Comparative Analysis: iPad Air vs. iPad Pro
To understand the significance of this move, one must examine the current hardware standing. The current iPad Air M4, launched in March 2026, utilizes a Liquid Retina IPS display with standard LED backlighting. While this display remains highly capable—offering P3 wide color gamut support, True Tone, and compatibility with the Apple Pencil Pro—it lacks the instantaneous pixel response and absolute contrast of OLED.
The technological differentiation is clear:
- iPad Pro: Employs Tandem OLED with LTPO (Low-Temperature Polycrystalline Oxide) backplanes. This enables variable refresh rates (ProMotion) and higher peak brightness, catering to professionals, digital artists, and power users.
- iPad Air: Expected to adopt Single-Stack OLED with LTPS backplanes. This configuration provides a significant leap over LCD technology while remaining more cost-effective, perfectly positioning the device as the "sweet spot" for students, creatives, and general consumers who do not require the extreme overhead of the Pro series.
Implications for the Broader Tablet Market
The decision to bring OLED to the iPad Air will likely force competitors in the Android tablet space to accelerate their own display upgrades. As Apple creates a new baseline for what constitutes a "mid-range" tablet screen, the industry-wide pressure to move away from LCDs in the $500–$800 price bracket will intensify.
Furthermore, this move solidifies the reliance on South Korean display expertise. By allocating the bulk of the iPad Air and iPad mini orders to Samsung Display, and the iPad Pro orders to a combination of Samsung and LG Display, Apple is reinforcing a long-term dependence on a specialized duopoly. While the inclusion of BOE as a potential third supplier serves as a hedge against supply chain disruptions and a tool for price negotiation, the heavy lifting of production remains concentrated within the mature OLED ecosystems of Korea.
A Note on Market Projections
It is essential to clarify that the figures cited—4 to 5 million units for the iPad Air, 4 to 5 million for the iPad mini, and 3 to 4 million for the iPad Pro—are current industry projections rather than confirmed sales targets from Cupertino. These estimates represent the manufacturing capacity and supply chain orders necessary to meet projected market penetration. Apple’s official stance remains one of silence regarding unannounced hardware. As is customary, the company has not provided details on specific display contracts, nor have they confirmed the exact technological composition of future iPad models.
The success of the 2027 iPad Air will ultimately hinge on whether the performance gains of OLED, combined with the expected processing power of future iterations of the Apple Silicon M-series chips, justify the potential price premiums associated with these upgraded components. For now, the supply chain is moving in one direction: the total transition to OLED is not merely a possibility for the iPad lineup—it is an inevitability. As manufacturing processes mature and yields improve, the cost gap between LCD and OLED will continue to narrow, making the transition not just a premium luxury, but a standardized feature of the modern digital tablet experience.
