The debate surrounding Indonesia’s fiscal architecture has intensified as lawmakers deliberate the proposed revision of Law Number 17 of 2003 concerning State Finances. Amid growing discussions over how to finance ambitious national development projects and stimulate higher economic growth, the Prosperous Justice Party (PKS) has issued a firm stance regarding the sacred fiscal boundaries established in the aftermath of the 1997-1998 Asian Financial Crisis. Specifically, the party has formally rejected any notion of relaxing the statutory state budget deficit ceiling, which currently caps the fiscal deficit at a maximum of 3 percent of the Gross Domestic Product (GDP).
The controversy centers on whether the longstanding 3 percent rule remains relevant in a rapidly evolving global and domestic economic landscape, or whether it has become an unnecessary constraint on government expansionary policies. While proponents of a relaxed fiscal threshold argue that greater budgetary flexibility is essential to fund strategic infrastructure, social safety nets, and economic transformation agendas, fiscal conservatives and opposition lawmakers maintain that abandoning the threshold risks destabilizing the nation’s macroeconomic foundations. As discussions continue in the House of Representatives (DPR), the focal point remains on finding a delicate balance between aggressive economic stimulation and long-term fiscal prudence.
The Legislative Battleground: Defend or Relax the 3 Percent Rule?
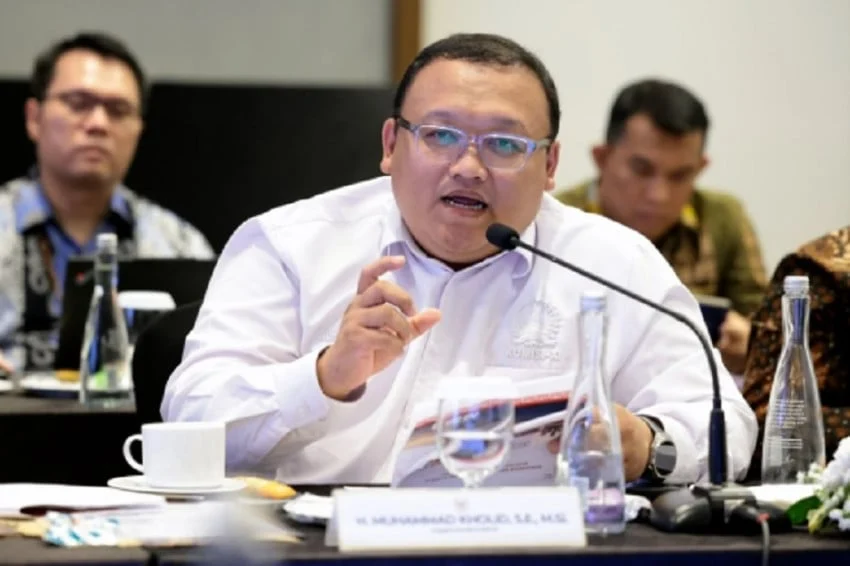
The core of the legislative dispute emerged during discussions within Commission XI of the DPR, which oversees financial affairs, national development planning, banking, and non-bank financial institutions. Muhammad Kholid, a prominent member of Commission XI representing the PKS faction, voiced strong opposition to proposals suggesting an upward revision or complete flexibility of the 3 percent deficit-to-GDP ratio.
Speaking on developments surrounding the State Finance Law revision, Kholid acknowledged the noble intentions driving the proposals. Lawmakers and policymakers advocating for a higher deficit limit typically argue that Indonesia requires massive capital injections to break out of the middle-income trap and achieve sustained high economic growth. However, Kholid emphasized that short-term stimulus should not come at the expense of structural fiscal health.
"We understand and appreciate the spirit to drive higher economic growth. That is a goal we share together. However, we view that the maximum deficit limit of 3 percent of GDP is still necessary to control debt in order to maintain fiscal sustainability and credibility," Kholid stated.
According to the PKS lawmaker, maintaining disciplined boundaries on the state budget (APBN) and keeping public debt accumulation under strict surveillance serves as the foundational bedrock for sound macroeconomic governance. A disciplined fiscal framework assures international rating agencies, foreign investors, and domestic financial markets that Indonesia remains committed to prudent financial management, thereby insulating the economy from external shocks and currency volatility.
Historical Context and the Origin of the 3 Percent Threshold
To understand the weight of the current debate, it is essential to examine the historical origins of the 3 percent fiscal deficit limit in Indonesia. Prior to the devastating Asian Financial Crisis of 1997-1998, Indonesia lacked a strict statutory ceiling for budgetary deficits, leading to unmonitored fiscal expansions and heavy reliance on external debt that ultimately triggered severe economic collapse.
In the wake of the crisis, as part of sweeping structural and institutional reforms aimed at restoring economic stability and rebuilding investor confidence, the Indonesian government enacted foundational legislative safeguards. Chief among these was Law Number 17 of 2003 concerning State Finances, alongside Law Number 1 of 2004 concerning the State Treasury and Law Number 15 of 2004 concerning Auditing of State Financial Management and Responsibility.
Law Number 17 of 2003 explicitly institutionalized the golden rules of fiscal management. Article 12 and Article 17 of the law mandated that the state budget must be prepared with a deficit limit capped at a maximum of 3 percent of GDP, while cumulative government debt was restricted to a maximum of 60 percent of GDP. These thresholds were not chosen arbitrarily; they mirrored internationally recognized prudential benchmarks, such as the Maastricht Treaty criteria in Europe, designed to prevent runaway public debt accumulation and runaway inflation.

For over two decades, this legal framework has served as Indonesia’s fiscal anchor. Even during periods of intense global turbulence—such as the 2008 Global Financial Crisis and the unprecedented COVID-19 pandemic—the 3 percent rule proved its worth. Notably, during the pandemic in 2020, the government invoked a temporary, legally sanctioned emergency clause via Perppu Number 1 of 2020 (later enacted as Law Number 2 of 2020), which permitted the widening of the fiscal deficit beyond 3 percent for three consecutive fiscal years (2020–2022) to finance emergency healthcare responses and massive social protection programs. However, this exception was strictly time-bound, and Indonesia successfully restored the deficit below the 3 percent threshold by the end of fiscal year 2023, showcasing remarkable fiscal consolidation praised by international institutions like the International Monetary Fund (IMF) and the World Bank.
Economic Arguments: Flexibility versus Discipline
The current debate over revising the State Finance Law has reopened ideological and technical divisions among economic policymakers, academicians, and political factions.
Proponents of relaxing the 3 percent ceiling argue that Indonesia’s development financing needs far exceed the revenue-generating capacity currently afforded by the state tax system. With an ambitious tax-to-GDP ratio that has historically hovered around 10 percent, the government often finds its hands tied when attempting to allocate sufficient funds for large-scale infrastructure, energy transition, human capital development, and free nutritional meal programs. Advocates for flexibility contend that adhering rigidly to a 3 percent cap forces the government to rely heavily on conservative spending cuts or aggressive borrowing at high interest rates during periods of global economic tightening. They suggest that a modernizing economy requires a dynamic fiscal rule that can scale up investments during critical windows of opportunity.
Conversely, fiscal conservatives and critics of relaxation—echoing the stance of PKS—warn that altering the sacred 3 percent boundary could unleash a slippery slope of undisciplined spending. Key points raised by defenders of the current limit include:
- Sovereign Credit Ratings: International rating agencies such as Moody’s, Standard & Poor’s, and Fitch closely monitor Indonesia’s fiscal discipline. Breaching or permanently raising the deficit ceiling could trigger a downgrade in Indonesia’s sovereign credit rating, increasing borrowing costs for both the government and the corporate sector.
- Debt Servicing Burden: A higher deficit inherently means higher annual borrowing. As government debt grows, the portion of the state budget allocated to debt interest payments also expands, crowding out essential productive expenditures such as education, healthcare, and infrastructure maintenance.
- Macroeconomic Stability: Maintaining strict fiscal boundaries acts as a credible signal to the market that monetary policy (managed by Bank Indonesia) and fiscal policy (managed by the Ministry of Finance) are working in tandem to control inflation and stabilize the rupiah exchange rate against external pressures.
Implications of the State Finance Law Revision
The ongoing deliberation over the revision of Law Number 17 of 2003 is more than a technical legislative exercise; it is a defining moment that will shape Indonesia’s economic trajectory for decades to come. As the government seeks to navigate complex global economic headwinds, including geopolitical tensions, fluctuating commodity prices, and high global interest rates, the preservation of institutional credibility is paramount.
If the legislature ultimately decides to maintain the 3 percent deficit ceiling—backed by the persistent reminders of political factions like PKS—the government will be forced to pursue alternative strategies to finance its development agenda. These strategies would likely necessitate aggressive structural reforms to enhance state revenue collection, plug tax leakages, digitalize administrative compliance, and expand the tax base without imposing undue burdens on ordinary citizens. Furthermore, it would place a premium on optimizing state-owned enterprise (SOE) performance, leveraging public-private partnerships (PPPs), and attracting foreign direct investment (FDI) to share the heavy lifting of national development.
On the other hand, should a compromise be reached that introduces conditional or formula-based flexibility—such as allowing wider deficits under strictly defined catastrophic or transformative conditions—policymakers will bear an immense burden of proof to design airtight accountability mechanisms. These mechanisms would need to ensure that any departure from the traditional norm is temporary, transparent, and strictly tied to high-multiplier economic outputs rather than recurring operational expenditures.
Conclusion
As the legislative process regarding the revision of the State Finance Law moves forward in the DPR, the debate over fiscal boundaries serves as a vital democratic forum for weighing competing economic philosophies. While the allure of immediate growth through expanded deficit spending remains strong among certain policymakers, cautionary voices like that of Muhammad Kholid and the PKS faction serve as an essential reminder of the hard-won lessons of past economic crises.
Maintaining fiscal sustainability and credibility is not merely about adhering to arbitrary numbers; it is about preserving the long-term economic sovereignty and resilience of the nation. Whether Indonesia chooses to strictly uphold the historical 3 percent deficit-to-GDP ratio or adapt its fiscal rules to modern realities, the ultimate test will lie in the government’s ability to balance visionary national development with unwavering fiscal discipline.
